
Covered Interest Parity Forwards
Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink Math
Linearly interpolating FX swap points between 1M and 2M tenors across an FOMC or BoJ rate decision misprices broken-date corporate forwards because overnight rates jump as a step function on the meeting date.
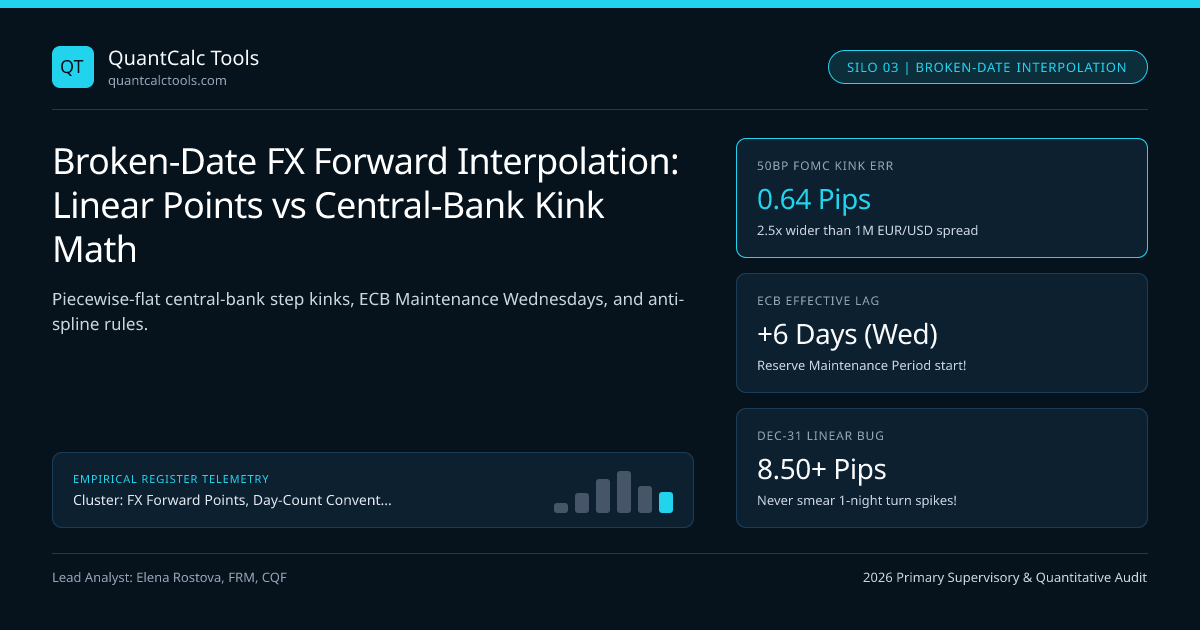
Corporate treasurers rarely hedge invoices landing neatly on standard 1M, 2M, or 3M interbank pillar dates—an exporter needs a 43-day "broken-date" (odd-date) FX forward settling on November 19th! If a junior desk script prices Day 43 by linearly interpolating swap points between Day 30 (1M) and Day 61 (2M) when an FOMC or ECB rate cut sits on Day 35, a sharp algorithmic client will pick off the desk instantly! Why? Because central-bank policy target rates (SOFR, €STR, SONIA, TONA) change as discrete step functions on exact Maintenance Period / Reserve Effective Dates, creating sharp slope kinks in the FX forward-points curve! Test exact forward tenors in our FX forward points & carry calculator and ground full parity principles in our Covered Interest Parity & FX Forward Points master guide.
Piecewise-Flat Forward Differential Step Kinks vs Naive Linear Interpolation#
Let $\delta1 = r{q,1} - r{b,1}$ denote the annualized interest-rate differential before central-bank effective date $T{\text{CB}}$ ($d{\text{CB}}$ days from Spot), and $\delta2 = r{q,2} - r{b,2}$ denote the new post-meeting differential after $T{\text{CB}}$! For any broken maturity $d$ inside $[d1, d2]$ where $d1 < d{\text{CB}} < d2$:
- Naive Linear Swap-Point Interpolation (WRONG across meetings!): Assumes a single constant average slope $\bar{\delta}$ across the entire month $[d1, d2]$:
$$\text{Points}{\text{linear}}(d) = \text{Points}(d1) + \frac{d - d1}{d2 - d1}\big[\text{Points}(d2) - \text{Points}(d_1)\big]$$
- Exact Meeting-Date Step Interpolation (Piecewise-Flat Overnight OIS): Accrues pre-meeting rate $\delta1$ strictly up to $d{\text{CB}}$, then switches slope to $\delta2$ after $d{\text{CB}}$:
$$\text{Points}{\text{exact}}(d) = \begin{cases} \text{Points}(d1) + S \cdot \delta1 \cdot \dfrac{d - d1}{360}\,M{\text{pip}}, & d1 \le d \le d{\text{CB}} \\[8pt] \text{Points}(d{\text{CB}}) + S \cdot \delta2 \cdot \dfrac{d - d{\text{CB}}}{360}\,M{\text{pip}}, & d{\text{CB}} < d \le d_2 \end{cases}$$
Worked 43-Day Broken-Date EUR/USD Forward Pricing Across a -50 bps FOMC Cut!#
- Market Pillar Quotes (Spot EUR/USD S = 1.08500):
- 1M Pillar (d1 = 30 days): Pre-FOMC Regime -> SOFR = 4.55%, ESTR-basis = 2.55% (Diff delta1 = +2.00% = +0.6028 pips/d)
- > Quoted 1M Swap Points (30 days) = +18.08 pips!
- FOMC Effective Date: Occurs at d_CB = 35 days! Market prices -50 bps jumbo Fed cut -> New SOFR = 4.05%!
- > Post-FOMC Diff delta_2 = 4.05% - 2.55% = +1.50% = +0.4521 pips/day (25% flatter slope!)
- 2M Pillar (d_2 = 61 days): 35 days @ +0.6028/d (+21.10p) + 26 days @ +0.4521/d (+11.75p)
- > Quoted 2M Market Swap Points (61 days) = +32.85 pips!
- Target Broken Date: Client Requests Day d = 35 (Right on FOMC Effective Date, BEFORE post-cut days accrue!):
- 1) Naive Linear Interpolation Between 1M (30d = +18.08p) and 2M (61d = +32.85p):
- Points_linear(35) = 18.08 + (5 / 31) * (32.85 - 18.08) = 18.08 + 2.38 = +20.46 pips!
- 2) Exact Piecewise-Flat OIS Step Formula (5 full days at pre-cut +0.6028 pips/d):
- Points_exact(35) = 18.08 + 5 * (0.6028) = +21.10 pips!
- 3) Broken-Date Pricing Error at Kink Vertex (d = 35):
- Error = +21.10 - 20.46 = +0.64 PIPS! (Wider than entire 0.25-pip EUR/USD interbank 1M bid-ask spread!)
- On a €200,000,000 institutional swap -> $12,800 instant adverse-selection loss on ONE ticket!
Look at Step 3: right at the meeting-date vertex ($d = 35$), linear interpolation misses the kink by $0.64$ pips—$2.5\times$ the entire interdealer 1M bid-ask spread (0.25 pips)! On a USD/JPY 50 bps BoJ/FOMC divergence (S = 154.00), that exact same single-meeting kink error balloons to nearly $1.00$ full JPY pip ($0.98$ pips)!
Subtle Central-Bank Effective-Date Traps: FOMC (Thu) vs ECB (Reserve Maintenance Wed)!#
Read those second and third KPI cards carefully—this trips up even seasoned fixed-income developers!
- Federal Reserve (
FOMC) & Bank of England (MPC): Announce policy rates on Wednesday (FOMC) or Thursday (BoE), and the new overnight rate (SOFR/SONIA) takes effect the very next business day! - European Central Bank (
ECB): Announces policy decisions on a Thursday, yet the new Deposit Facility Rate (€STR) DOES NOT TAKE EFFECT ON FRIDAY! It takes effect six days later on the start of the new Eurosystem Reserve Maintenance Period (Wednesday)! Coding ECB rate jumps on Friday instead of Maintenance Wednesday creates a 5-day broken-date pricing error across every single ECB meeting! Check compounded SOFR accruals in our SOFR overnight compounding & carry calculator.
Broken-Date Interpolation Methods Compared Across Market Conditions#
| Curve Interpolation Method | Handles CB Rate Cuts/Hikes? | Handles Dec-31 Turn Spikes? | Arbitrage-Free Across Pillars? | Suitable Institutional Scope |
|---|---|---|---|---|
| Linear on Swap Points | FAILS (Misses kink up to 1+ pip) | FAILS BADLY (Smears 1d spike!) | No | Back-office approximate mid-checks only |
| Log-Linear on Discount Factors | FAILS (Flat continuous fwd) | FAILS BADLY | Smooth but ignores calendar | Long tenors $> 1\text{Y}$ without turns |
| Cubic Spline on Zero Yields | DANGEROUS (Oscillates at step!) | OSCILLATES WILDLY | Ringing artifacts | NEVER use on $< 1\text{Y}$ FX forwards! |
| Meeting-Date Piecewise-Flat + Turns | EXACT (Captures Thu/Wed kinks) | EXACT (Dirac 1-day jump) | 100% Arbitrage-Free | Tier-1 e-FX Auto-Pricing Engines |
Pairing Central-Bank Kinks with Year-End Turn Spikes & Corporate Window Forwards#
Look at that fourth bar (8.50+ Pips! across Dec 30 vs Jan 2): smearing an overnight December 31 balance-sheet spike linearly across all 31 days of December is catastrophic—master exact Dirac turn impulse math next in quarter-end and year-end G-SIB window-dressing FX swap turns, price flexible corporate delivery windows in FX time-option window forwards, and explore the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Why does the maximum broken-date linear interpolation error always occur right on the central-bank effective date?
The true cumulative forward-points curve consists of two straight segments meeting at a kink on day d_CB, while linear interpolation draws a chord connecting the endpoints d_1 and d_2. Geometrically, the vertical distance between a two-segment angle and its secant chord peaks strictly at the vertex d_CB!
Why does an ECB Thursday interest-rate cut not change EUR/USD overnight swap points until the following Wednesday?
Under Eurosystem monetary operations rules, changes to the ECB Deposit Facility Rate (which anchors €STR) only become effective on the first day of the new Reserve Maintenance Period—always the Wednesday following the Governing Council meeting!
How do interbank FX swap desks trade central-bank meeting dates directly?
Interdealer brokers quote "FOMC-dated" and "ECB-dated" forward-starting OIS and FX swaps (spanning purely from one meeting effective date to the next), allowing e-FX engines to strip exact implied step jumps in real time.
When is simple linear interpolation of FX swap points acceptable?
Only when the broken date and its two bracketing liquid pillars (say 2M and 3M, or 4M and 5M) span zero central-bank meetings with priced rate changes AND zero quarter-end or year-end balance-sheet reporting dates.
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 15). Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink Math. QuantCalc Tools. https://quantcalctools.com/guides/broken-date-fx-forward-linear-interpolation-central-bank-turn-kinksRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
Quarter-End & Year-End G-SIB Window-Dressing FX Swap Turn Premium MathCovered Interest Parity Forwards
SOFR, ESTR & SONIA OIS Compounded In-Arrears FX Forward Discounting MathCovered Interest Parity Forwards
FX Carry-to-Volatility Ratio, Forward Discount Puzzle & Breakeven Spot MathCovered Interest Parity Forwards
Non-Deliverable Forward (NDF) Cash Settlement & Implied Offshore Yield MathCovered Interest Parity Forwards
Historic-Rate vs Market-Rate FX Swaps: Uneven Notional & NPV Tail MathCovered Interest Parity Forwards
Cross-Rate Triangular FX Forward Arbitrage & Bid-Ask Swap Bounds MathCovered Interest Parity Forwards
Continuous Garman-Kohlhagen vs Discrete Money-Market CIP FX Options MathCagr Irr Drawdown Compounding
Sortino Ratio & Target Downside Semi-Deviation (MAR): Exact LPM2 MathCagr Irr Drawdown Compounding
Calmar, Sterling & Ulcer Performance Index: Path-Dependent Drawdown MathCagr Irr Drawdown Compounding
Omega Ratio Threshold Partition (LPM1): Full-Distribution Skew & Kurtosis MathCagr Irr Drawdown Compounding
Probabilistic & Deflated Sharpe Ratio (DSR): Backtest Multiple-Testing Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.