
Covered Interest Parity Forwards
Basel SA-CCR & ISDA SIMM v2.6 FX Forward Margin & Capital Drag Math
Physical FX forwards and swaps enjoy a statutory Uncleared Margin Rules (UMR) Initial Margin exemption, yet trigger punitive Basel SA-CCR 4% notional capital charges and XVA pricing spreads.
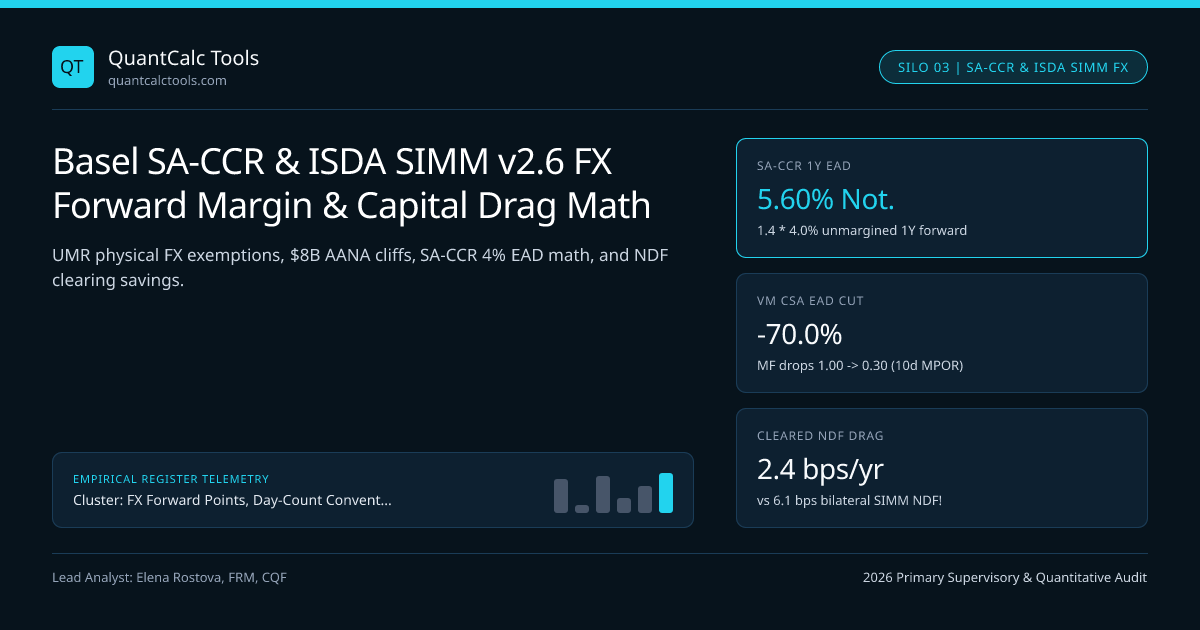
Here is one of the most consequential regulatory asymmetries in global finance: under BCBS-IOSCO Uncleared Margin Rules (UMR), physically settled FX Forwards and FX Swaps are EXEMPT from mandatory Initial Margin (IM)—whereas FX Options and EM Non-Deliverable Forwards (NDFs) MUST post ISDA SIMM v2.6 Initial Margin once group Aggregate Average Notional Amount (AANA) exceeds $8 billion / €8 billion (AND still count toward that $8B AANA threshold)! Meanwhile, on bank balance sheets, Basel III CRE52 (SA-CCR, Standardized Approach for Counterparty Credit Risk) slaps a flat $4.0\%$ Supervisory Factor on FX forward notionals—driving KVA (Capital Valuation Adjustment) directly into the Covered Interest Parity basis! Test baseline swap points in our FX forward points & carry calculator and review parity fundamentals in our Covered Interest Parity & FX Forward Points master guide.
Exact Basel III CRE52 SA-CCR Exposure-at-Default (EAD) Formula for FX Forwards#
Under Basel CRE52, a bank's Counterparty Credit Risk Exposure at Default (EAD) on a netting set of FX forwards equals $\alpha = 1.4$ times Replacement Cost (RC) plus Potential Future Exposure (PFE): $$EAD{\text{SA-CCR}} = 1.4 \times (RC + \text{Multiplier} \times AddOn{\text{FX}}), \qquad AddOn{\text{FX}}^{(k)} = SF{\text{FX}} \times |\deltak \cdot dk^{\,\text{FX}} \cdot MF_k|$$ Plug in the exact statutory CRE52 FX parameters:
- FX Supervisory Factor ($SF_{\text{FX}}$): Strictly $4.0\%$ ($0.040$) for ALL currency pairs (whether ultra-stable
EUR/DKKor volatileUSD/TRY!). - Maturity Factor ($MF_k$):
- Unmargined Corporate Client: $MF{\text{unmargined}} = \sqrt{\frac{\min(Mk, 1.0\text{ yr})}{1.0\text{ yr}}}$ (equals $0.500$ for a 3-month forward, $1.000$ for $\ge 1\text{Y}$!).
- Daily VM-Margined Institutional Client (
MPOR = 10 business days): $MF_{\text{margined}} = \frac{3}{2}\sqrt{\frac{10}{250}} = \mathbf{0.3000}$!
Worked $100M 1-Year EUR/USD Forward SA-CCR KVA vs NDF ISDA SIMM MVA Audit#
- Part A — Basel SA-CCR Capital Charge (KVA) on Unmargined Corporate vs VM-Margined Hedge Fund (1Y EUR/USD Fwd):
- Inception MTM = $0 (RC = 0, Multiplier = 1.0); FX Supervisory Factor SF_FX = 4.0%
- 1) Unmargined BBB Corporate Client (Risk Weight RW = 75%, MF = sqrt(1/1) = 1.000):
- AddOn_FX = 0.040 * $100,000,000 * 1.000 = $4,000,000
- EAD = 1.4 * ($0 + $4,000,000) = $5,600,000 -> RWA = 75% * $5.60M = $4,200,000!
- Tier-1 Capital Required (11.5% CET1) = $483,000; At 12% Bank ROE Hurdle (minus 4.5% RFR = 7.5% spread):
- ANNUAL KVA PRICING CHARGE = $483,000 * 7.5% = $36,225 = +3.62 PIPS (+3.62 bps) ON 1Y FORWARD!
- 2) Daily VM-Margined Institutional Fund (RW = 50%, MPOR = 10d -> MF = 0.3000):
- AddOn_FX = 0.040 * $100,000,000 * 0.3000 = $1,200,000 -> EAD = 1.4 * $1.20M = $1,680,000 (-70% EAD!)
- RWA = $840,000 -> CET1 = $96,600 -> ANNUAL KVA = $7,245 = +0.72 PIPS (-80% CHEAPER!)
- Part B — ISDA SIMM v2.6 Initial Margin & MVA on $100M 1Y USD/KRW Non-Deliverable Forward (UMR In-Scope!):
- Note: Deliverable EUR/USD Forward IM = $0 (UMR Exempt!); Cash-Settled USD/KRW NDF MUST Post SIMM IM!
- ISDA SIMM v2.6 Regular FX Risk Weight (~7.4%–8.1% bilateral USD/KRW): IM_SIMM ~= $7,800,000 PER SIDE!
- Funding $7.80M Initial Margin at +65 bps Treasury/Funding Spread => MVA = $50,700/yr (+5.07 bps drag — unless cleared!)
Look at the two massive institutional takeaways in that calculation:
- Signing a daily Variation Margin (
VM) CSA slashes a dealer's SA-CCR Maturity Factor from1.00down to0.30—cuttingKVAcapital drag on 1-year FX forwards by-80%(3.62 pips -> 0.72 pips)! - On EM NDFs and FX Options, bilateral uncleared ISDA SIMM v2.6 Initial Margin demands
~$7.80Mper$100M(+5.07 bpsMVA drag)—which is why clearing NDFs at LCH ForexClear (5-day MPORvs10-day bilateral MPOR, cutting IM by~45%and dropping CCP Risk Weight to2%vs50%–75%!) dominates modern NDF execution!
The $8 Billion UMR AANA Trap & Why Multilateral FX Compression Boomed!#
Read Step 1 and Step 2 carefully—hedge funds and pension funds get blindsided by both rules:
- The UMR
AANACounting Trap: Even though physically settled FX swaps and forwards pay $0.00 Initial Margin, 100% of their gross notional STILL COUNTS toward your firm's March–May$8 Billion / €8 BillionUMR Phase 6AANAthreshold! A macro fund holding$7.5Bof harmless G10 FX swaps and$600Mof equity/NDF swaps crosses$8.0B—triggering full custodial ISDA SIMM IM compliance on all non-exempt derivatives! - The SA-CCR Cross-Pair Netting Trap: Suppose you bought
€100M EUR/USD(+$108M) and sold€100M EUR/GBP+ bought£85M GBP/USD—economically zero net FX risk ($0SIMM)! Under SA-CCR,CRE52computesAddOn_FXseparately per currency pair and sums them with ZERO cross-pair correlation offset—charging 3x capital until compressed via TriOptima / Quantile multilateral FX compression cycles!
Regulatory Treatment Matrix Across FX Product Types (UMR, SA-CCR & Clearing)#
| FX Instrument Type | Counts in $8B UMR AANA? | Mandatory UMR Initial Margin (SIMM)? | Mandatory Variation Margin (VM)? | Basel SA-CCR Add-On (SF = 4%) |
|---|---|---|---|---|
Spot FX (<= T+2) | No (Not a derivative) | No ($0) | No | $0.00$ (Settlement risk only) |
| Physical FX Forward / Swap | YES (100% Gross!) | EXEMPT ($0 IM) | Guideline / CSA dependent | Full $4.0\% \times MF \times 1.4$! |
| Cross-Currency Swap (Principal) | YES | EXEMPT on FX Principal (IM on IR!) | YES (Daily VM) | $4.0\%$ FX + IR Add-On |
EM Non-Deliverable Forward (NDF) | YES | YES (Full ISDA SIMM ~7–9%!) | YES (Daily VM) | Full $4.0\%$ (or $2\%$ RW if Cleared!) |
| Vanilla & Exotic FX Options | YES | YES (SIMM Delta + Vega + Curv!) | YES (Daily VM) | Black-Scholes $\Delta$-weighted $4.0\%$ |
Connecting SA-CCR & SIMM to Cross-Currency Basis & Seasoned MTM Valuation#
Now the macro puzzle comes full circle: that 0.9 to 5.8 bps SA-CCR RWA drag plus G-SIB leverage surcharge IS the exact microeconomic cost floor preventing banks from arbitraging away cross-currency basis swap CIP deviations and driving December spikes in quarter-end and year-end G-SIB FX swap turns! Audit UK/EU prudential rules via the UK Prudential Regulation Authority, test portfolio VaR in our Value-at-Risk calculator, and browse the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Why did global regulators exempt physically settled FX forwards and swaps from mandatory Initial Margin (UMR)?
The US Treasury Determination (2012) and BCBS-IOSCO recognized that FX swaps have fixed short maturities, full principal exchange governed by CLS Payment-versus-Payment (PvP) settlement, and serve as short-term treasury funding rather than speculative leverage.
Wait—why does a Cross-Currency Swap pay Initial Margin on its INTEREST RATE risk if its FX principal is exempt?
Under BCBS-IOSCO UMR rules, the fixed-for-floating or basis INTEREST-RATE component of a cross-currency swap is NOT exempt from ISDA SIMM Initial Margin—only the final FX principal exchange sensitivity is excluded from the SIMM FX delta grid!
How does ISDA SIMM v2.6 calculate FX Initial Margin across a multi-currency NDF and option portfolio?
ISDA SIMM converts every non-calculation-currency net FX sensitivity (1% spot shift PV impact) into USD, applies currency-category risk weights (~7.4%–8.1% regular, higher for high-volatility EM currencies), and aggregates via a 0.50 cross-currency correlation matrix.
How do dealers compress SA-CCR FX forward notional without altering client positions?
Multilateral compression services (OSTTRA triReduce, LSEG Quantile) run linear programs across 30+ dealer banks to tear up offsetting EUR/USD, USD/JPY, and cross forward triangles and replace them with tiny net-delta forward stubs, cutting gross notional by 40%–70%.
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). Basel SA-CCR & ISDA SIMM v2.6 FX Forward Margin & Capital Drag Math. QuantCalc Tools. https://quantcalctools.com/guides/sa-ccr-isda-simm-fx-forward-margin-drag-capital-cost-basis-pricingRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
Mark-to-Market (MTM) Valuation of Seasoned FX Forwards: Discounted PV MathCovered Interest Parity Forwards
ACT/360 vs ACT/365 FX Forward Day-Count Mismatch: GBP/USD & USD/CAD MathCovered Interest Parity Forwards
JPY 100 Pip Multiplier vs 10,000 Four-Decimal FX Forward Points MathCovered Interest Parity Forwards
Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge MathCovered Interest Parity Forwards
Overnight (O/N), Tom-Next (T/N) & Spot-Next (S/N) T+2 FX Roll MathCovered Interest Parity Forwards
Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink MathCovered Interest Parity Forwards
Quarter-End & Year-End G-SIB Window-Dressing FX Swap Turn Premium MathCagr Irr Drawdown Compounding
Fisher Exact Real CAGR, Inflation & Annual Tax Drag Compounding MathKelly Margin Leverage Sizing
Discrete Binomial Kelly Criterion: Win Rate & Asymmetric Payoff ProofKelly Margin Leverage Sizing
Continuous Merton-Kelly Leverage ((mu - r_f)/sigma^2) & Half-Kelly MathKelly Margin Leverage Sizing
Multi-Asset Kelly Portfolio Sizing: Inverse-Covariance & Shrinkage Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.