
Covered Interest Parity Forwards
Historic-Rate vs Market-Rate FX Swaps: Uneven Notional & NPV Tail Math
Rolling a $100M foreign-currency hedge after a 10% spot move via a standard Even-Base FX swap triggers an immediate $10M cash liquidity drain; Uneven FX swaps neutralize spot cashflows via PV-adjusted points.
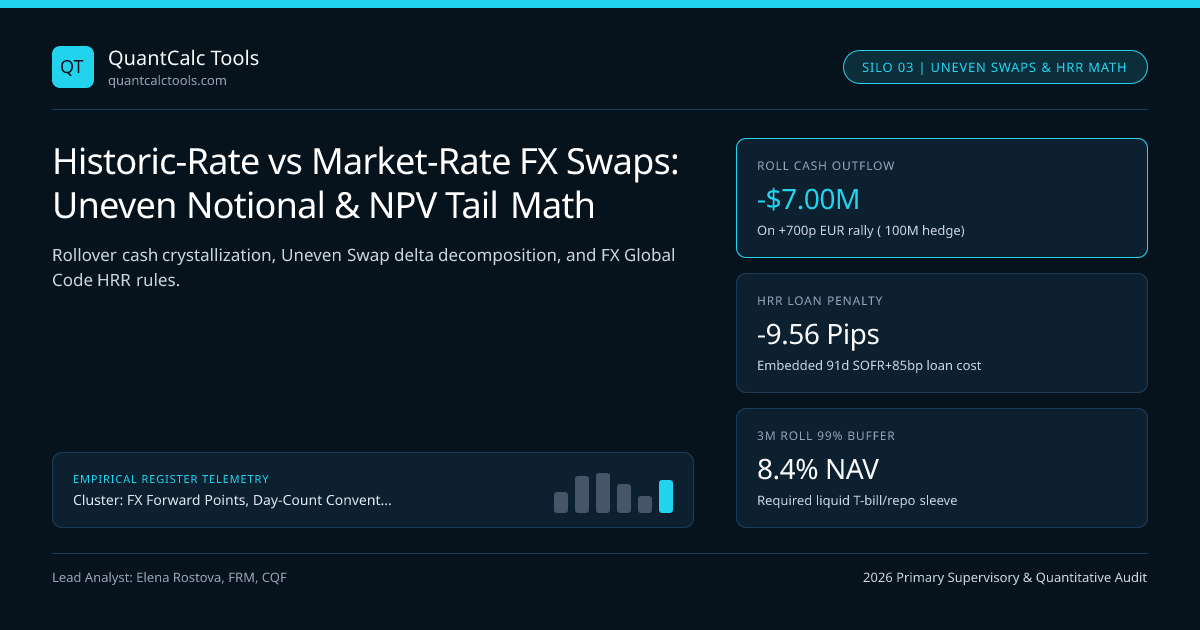
Suppose an asset manager hedged a €100,000,000 European bond portfolio three months ago by selling €100M forward at 1.0500 (+$105.00M USD inflow), and today at maturity EUR/USD spot has rallied to 1.1200! Rolling that hedge forward another 3 months via a standard Even-Notional FX Swap (Buy €100M Spot @ 1.1200 / Sell €100M 3M Fwd @ 1.1255) forces the fund to wire out $$112.00\text{M}$ USD today while receiving only $$105.00\text{M}$ USD on the maturing forward—triggering an immediate $-$7,000,000$ USD cash liquidity crunch even though the underlying bonds weren't sold! And what if the treasurer tries to fix the cash drain with an Uneven (Mismatched) FX Swap or illegal/restricted Historic-Rate Rollover (HRR)? Both alter forward points via exact NPV Interest-Rate Tail Adjustments! Check baseline swap points in our FX forward points & carry calculator and review parity fundamentals in our Covered Interest Parity & FX Forward Points master guide.
Three Ways to Roll a Seasoned FX Forward: Even-Base vs Even-Quote vs Historic-Rate!#
When rolling an expiring forward ($Nb = €100\text{M}$ at old strike $K0 = 1.0500$, settling against live Spot $S = 1.1200$ and standard 3-month Swap Points $P_{\text{std}} = F - S = +0.00550$):
- Standard Even-Base FX Swap (
€100MNear /€100MFar): Zero EUR cashflow at spot (+€100M - €100M = €0), but crystallizes $Nb(K0 - S) = -$7,000,000$ USD cash outflow today! - Mismatched / Uneven-Quote FX Swap (Matched USD Near Cashflow!): Sets near leg to
Buy €100M @ 1.1200(-$112M? Wait—if the client wants to keep USD notional constant at$105M, near leg buys€93.75Mleaving€6.25Mshort!). What if the client demands Historic-Rate Rollover (HRR)—settling the near leg at1.0500instead of1.1200so both EUR and USD cashflows today equal $0.00?! - Exact Historic-Rate Rollover (
HRR) Pricing Formula:Settling the near leg at $K0 = 1.0500$ instead of $S = 1.1200$ means the bank **lends the client $$7,000,000$ USD on an unsecured basis from $T{\text{spot}}$ to $T{\text{fwd}}$**! To keep bank NPV $= 0$, that $$7.00\text{M}$ embedded loan compounds at USD funding rate $r{\text{USD}} + s{\text{credit}}$ and gets deducted from the far forward rate $F{\text{HRR}}$:
$$F{\text{HRR}} = F{\text{mkt}} - (S - K0)\left(1 + (r{\text{USD}} + s{\text{credit}})\frac{d}{360}\right) = K0 + P{\text{std}} - (S - K0)\,(r{\text{USD}} + s{\text{credit}})\frac{d}{360}$$
Worked €100M Rollover Liquidity & Embedded Credit-Loan Audit#
- Market Inputs:
- 91-Day USD SOFR OIS = 4.55% (ACT/360); EUR ESTR (incl. basis) = 2.58% (ACT/360)
- Standard Market 3M Outright F_mkt = 1.12000 * (1 + 0.045591/360) / (1 + 0.025891/360) = 1.12554 (+55.4 pips)
- 1) Standard Market-Rate Even-Base Swap (Near = 1.12000, Far = 1.12554):
- Immediate Spot Cash Settlement = €100M * (1.05000 - 1.12000) = -$7,000,000 USD Cash Outflow TODAY!
- New 3M Forward Contracted USD Proceeds = €100M * 1.12554 = $112,554,000 (Clean credit profile, 0 inception PV)
- 2) Off-Market Historic-Rate Rollover (Near = 1.05000 -> ZERO Cash Outflow Today; Bank Credit Spread = +85 bps):
- Client Borrows $7,000,000 Implicitly at r_loan = 4.55% + 0.85% = 5.40% (ACT/360) for 91 days!
- 91-Day Interest + Principal on $7.00M Loan = $7,000,000 * (1 + 0.0540 * 91 / 360) = $7,095,550
- Per-Euro Deduction at 3M Maturity = $7,095,550 / €100,000,000 = 0.0709555 USD/EUR
- Exact HRR 3M Forward Outright F_HRR = 1.125540 - 0.070956 = 1.054584!
- Check Net HRR "Roll Points" Over K_0 (1.05000): +45.84 pips (vs +55.40 market pips -> -9.56 PIPS PENALTY!)
- 3) Even-Forward-Value Uneven FX Swap (Matching Exact Future Bond Coupon + Principal = €102.50M Far vs €100M Near!):
- Swap Dealer Quotes Standard +55.40 Pips ONLY on €100M Matched Base; Extra €2.50M Far Leg Trades as Outright Fwd!
- Residual Spot Delta = €0 ONLY if Dealer Executes Extra €2.50M Spot Hedge Immediately!
Look at Step 2 (-9.56 PIPS PENALTY and $7.00M hidden loan!):
- Why do the ACI Model Code and FX Global Code (Principle 17 / Market Risk & Compliance) strictly prohibit Historic-Rate Rollovers unless approved in writing by Senior Credit, Legal, and CFO sign-off?! Because rogue corporate traders in the 1990s/2000s used HRRs to conceal massive mark-to-market FX losses off-income-statement for years while secretly borrowing millions from swap dealers!
Decomposing "Uneven (Mismatched) FX Swaps" Into Pure Swap + Outright Forward!#
In legitimate bond-fund management, your European bond portfolio grew from €100.0M to €102.5M over the quarter, so you ask a dealer to Buy €100.0M Spot and Sell €102.5M 3-Month Forward (Uneven FX Swap). Never assume an Uneven FX Swap is spot-neutral! $$\text{Buy } €100\text{M Spot} / \text{Sell } €102.5\text{M Fwd} \equiv \underbrace{(\text{Buy } €100\text{M Spot} / \text{Sell } €100\text{M Fwd})}{\text{Spot-Neutral FX Swap}} + \underbrace{(\text{Sell } €2.5\text{M Outright Fwd})}{\mathbf{-€2.5\text{M Live Spot Delta!}}}$$ The dealer must buy €2.5M in the live spot market (crossing spot bid-ask) to hedge that uneven tail! Check compounded funding costs on rollover cash buffers in our SOFR overnight compounding & carry calculator.
Comparing FX Hedge Rollover Structures Across Pension & Asset-Management Funds#
| Rollover Execution Structure | Today's USD Cashflow | Spot FX Delta Impact | Regulatory / Compliance Status | Optimal Institutional Use Case |
|---|---|---|---|---|
| Market-Rate Even-Base Swap | Crystallizes $-$7.00\text{M}$ | $0.00$ (Spot-neutral) | Gold Standard (Zero credit loan) | Liquid multi-asset funds with cash sleeves |
| Uneven Swap (NAV-Adjusted) | Crystallizes $-$7.00\text{M}$ | Sells €2.5M new gain | Standard (Dynamic NAV hedge) | Currency-hedged share classes (EUR->USD) |
Even-USD Swap ($105M Fixed) | $0.00$ Cashflow! | Under-hedges EUR by -6.25%! | Permitted (Leaves unhedged EUR!) | Fixed USD liability matching only |
Historic-Rate Rollover (HRR) | $0.00$ (Deferred loan) | $0.00$ | Restricted / Prohibited (FX Global Code) | Rare CFO-disclosed credit facilities |

Liquidity Spiral Prevention for Private-Credit & Hedged Sovereign Funds#
Look at that chart: closed-end private-equity and infrastructure funds holding $100\%$ illiquid assets cannot wire out $8.4\%$ of NAV in cash every quarter when foreign currencies rally! That exact trap pushes private funds toward SA-CCR and ISDA SIMM FX forward margin analysis, MTM resetting cross-currency swaps, and mark-to-market valuation of seasoned FX forwards. Explore all 20 guides on the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Why does the FX Global Code heavily restrict Historic-Rate Rollovers (HRRs)?
HRRs allow a corporate treasury employee to roll losing FX trades at old strikes without wiring out cash—hiding mark-to-market losses from auditors and boards while silently accumulating unsecured debt with the dealer bank.
How do currency-hedged ETF share classes (e.g., EUR-hedged S&P 500 ETFs) handle monthly FX swap cash outflows?
UCITS and 1940-Act currency-hedged ETFs use 1-month rolling forwards (keeping monthly cash settlements within ~2%–5% of NAV) and sell or buy a tiny slice of the liquid underlying equity basket on month-end rebalancing day to fund net swap settlements.
Does an Even-Base FX Swap have zero interest-rate DV01 risk?
No! While an Even-Base FX Swap has near-zero SPOT FX delta (~1%–4% forward-factor residual), it is 100% pure interest-rate differential DV01—long one currency’s zero-coupon deposit and short the other currency’s zero-coupon deposit!
How big is the residual Spot FX Delta of a "spot-neutral" Even-Base 1-Year FX Swap?
Because V_swap = N_base * [ S * DF_base(T) - F_0 * DF_quote(T) ], differentiating with respect to S gives Spot Delta = DF_base(T) - 1! At a 4.5% 1-year rate, a $100M "even" FX swap actually carries -$4.3M of residual Spot FX tail delta!
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 15). Historic-Rate vs Market-Rate FX Swaps: Uneven Notional & NPV Tail Math. QuantCalc Tools. https://quantcalctools.com/guides/uneven-fx-swap-mismatch-cashflow-npv-tail-interest-rate-exposureRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
Cross-Rate Triangular FX Forward Arbitrage & Bid-Ask Swap Bounds MathCovered Interest Parity Forwards
Continuous Garman-Kohlhagen vs Discrete Money-Market CIP FX Options MathCovered Interest Parity Forwards
Synthetic USD Commercial Paper Funding: FX Swap Implied SOFR Spread MathCovered Interest Parity Forwards
Currency-Hedged Foreign Sovereign Bond Yield Pickup: 3M Rolling FX Swap MathCovered Interest Parity Forwards
USD/CAD T+1 Spot Lag, Modified Following & End-of-Month FX Calendar MathCovered Interest Parity Forwards
FX Time-Option (Window) Forward Pricing: Worst-Case Swap Point Rule MathCovered Interest Parity Forwards
Mark-to-Market (MTM) Resetting Cross-Currency Basis Swap Notional MathCagr Irr Drawdown Compounding
Constant-Weight Rebalancing Bonus & Shannon Demon Dispersion MathCagr Irr Drawdown Compounding
Daily Leveraged ETF Beta Slippage & Volatility Decay Math (2x, 3x, -1x)Cagr Irr Drawdown Compounding
Information Ratio, Tracking Error & Grinold-Kahn Fundamental Law MathCagr Irr Drawdown Compounding
Expected Maximum Drawdown of Brownian Motion (Magdon-Ismail Drift Math)
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.