
Covered Interest Parity Forwards
JPY 100 Pip Multiplier vs 10,000 Four-Decimal FX Forward Points Math
Hardcoding 10,000 into an FX forward parser misprices USD/JPY and EUR/JPY swap points by a factor of 100x; master ISO pip multipliers, fractional pipettes, and percentage-to-pip conversions.
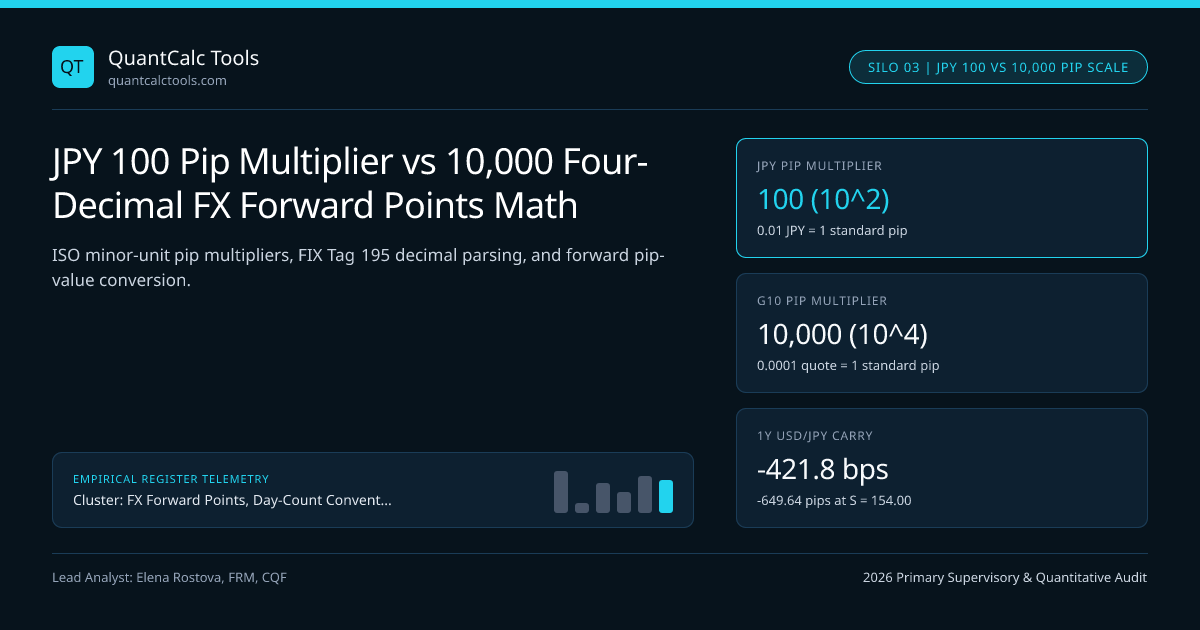
Nothing triggers an emergency risk-switch shutdown faster on a quantitative FX desk than hardcoding pip_scale = 10000 across a multi-currency basket and feeding -645.20 1-year USD/JPY forward points into F = S + points / 10000—computing a 1-year USD/JPY outright of 153.9355 instead of the true 147.5480 ($432,800 pricing catastrophe per $10M ticket)! Because one Japanese Yen is roughly one cent rather than one dollar, every FX pair with JPY as the quote currency uses a pip multiplier of $M_{\text{pip}} = 100$ ($10^2$, second decimal place) instead of $10{,}000$ ($10^4$, fourth decimal place)! Verify multi-pair pip conventions live in our FX forward points & carry calculator and ground full parity equations in our Covered Interest Parity & FX Forward Points master guide.
Exact Bi-Directional Conversion Between Decimal Outrights, Pips, Pipettes & Annualized bps#
For any currency pair BASE/QUOTE with spot rate $S$, outright forward $F$, holding horizon $d$ days, and quote-currency pip exponent $k{\text{pip}}$ ($k{\text{pip}} = 2 \implies M{\text{pip}} = 100$ for XXX/JPY, XXX/HUF, USD/KRW, USD/INR, USD/CLP; $k{\text{pip}} = 4 \implies M{\text{pip}} = 10{,}000$ for EUR/USD, GBP/USD, AUD/USD, USD/CAD, USD/CHF): $$\text{Points (pips)} = (F - S) \times 10^{k{\text{pip}}}, \qquad F = S + \frac{\text{Points (pips)}}{10^{k{\text{pip}}}}$$ And how do you compare -645.2 pips on USD/JPY against +214.8 pips on EUR/USD on a standardized annualized basis-point yield scale? Divide raw decimal forward spread $(F - S)$ by Spot $S$ and annualize! $$\text{Annualized Forward Carry (bps)} = \left(\frac{F - S}{S}\right) \times \frac{365}{d} \times 10{,}000 = \frac{\text{Points (pips)}}{S \times 10^{k{\text{pip}} - 4}} \times \frac{365}{d}$$
Worked Side-by-Side Scaling Audit: 1-Year EUR/USD vs USD/JPY ($10M USD Notional)#
- Inputs:
- Pair 1 — EUR/USD: Spot S1 = 1.08500 (4-decimal pip = 0.0001, 5th-decimal pipette = 0.00001; Mpip = 10,000)
- 1Y Rates: USD SOFR = 4.55% (ACT/360), EUR ESTR = 2.65% (ACT/360), XCCY Basis = -15 bps (on EUR leg -> 2.50%)
- Exact 1Y Outright F_1 = 1.08500 * [ (1 + 0.0455365/360) / (1 + 0.0250365/360) ]
- = 1.08500 * (1.046132 / 1.025347) = 1.106995
- Quoted Forward Points = (1.106995 - 1.08500) * 10,000 = +219.95 pips (+2,199.5 pipettes)
- Annualized % Carry = (+0.021995 / 1.08500) * 10,000 = +202.72 bps (+2.0272% / yr)
- Pair 2 — USD/JPY: Spot S2 = 154.000 (2-decimal pip = 0.01 JPY, 3rd-decimal pipette = 0.001; Mpip = 100!)
- 1Y Rates: JPY TONA = 0.45% (ACT/365F), USD SOFR = 4.55% (ACT/360), XCCY Basis = -25 bps (on JPY leg -> 0.20%)
- Notice: JPY is QUOTE (Numerator) and USD is BASE (Denominator)!
- Exact 1Y Outright F_2 = 154.000 * [ (1 + 0.0020365/365) / (1 + 0.0455365/360) ]
- = 154.000 * (1.002000 / 1.046132) = 147.5036
- Quoted Forward Points = (147.5036 - 154.000) * 100 = -649.64 PIPS! (-6.4964 JPY outright discount!)
- Annualized % Carry = (-6.4964 / 154.000) * 10,000 = -421.84 bps (-4.2184% / yr!)
- Check Dollar Value of 1 Pip on $10,000,000 USD Spot Equivalent:
- EUR/USD (€9,216,590 base): 1 pip = €9,216,590 * 0.0001 = $921.66 USD!
- USD/JPY ($10,000,000 base): 1 pip = $10,000,000 * 0.01 JPY = ¥100,000 JPY / 147.5036 (Fwd!) = $677.95 USD!
Look closely at the final line of that USD/JPY pip-value check: when settling a forward profit/loss at Year 1 on USD/JPY, 1 pip equals ¥100,000 JPY payable at the forward delivery date—so converting forward JPY PnL back into USD divides by the Forward Rate $F_2 = 147.5036$ ($677.95/pip), NOT the Spot Rate $S_2 = 154.000$ ($649.35/pip — a 4.4% PnL hedge error)!
Electronic Trading API Trap: FIX Tag 195 (LastForwardPoints) Decimal vs Pips!#
Algorithmic traders connecting via FIX API infrastructure, MetaTrader 5, or cTrader must enforce a mandatory sanity guard on incoming swap feeds:
- Under standard FIX 4.4 / 5.0 Tag
195(LastForwardPoints), institutional ECNs (EBS, Reuters Matching, 360T) transmit raw decimal price offsets (-6.4964for 1YUSD/JPY,+0.021995for 1YEUR/USD) soTag 64 SettlDateoutright equalsTag 194 LastSpotRate + Tag 195 LastForwardPointsdirectly! - Meanwhile, Bloomberg
FXFA/FRDscreens and voice brokers quote scaled pips (-649.64and+219.95), while retail MT5 swap tables quote pipettes (points = 1/10th pip:-6496.4and+2199.5)! Always run a runtime unit assertionMath.abs((F - S) / S) < 0.25for G10 tenors $\le 2\text{Y}$ before routing orders!
Global FX Pip, Pipette & Big-Figure Scaling Matrix Across Currency Pairs#
| Pair Category | Representative Pairs | 1 Standard Pip | $M_{\text{pip}}$ Multiplier | 1 Pipette ($0.1$ Pip) | 1 "Big Figure" ($100$ Pips) |
|---|---|---|---|---|---|
| Standard G10 Dollar | EUR/USD, GBP/USD, AUD/USD, USD/CHF, USD/CAD | $0.0001 | $10{,}000$ ($10^4$) | $0.00001 ($10^5$) | $0.0100 (1 cent) |
| Non-JPY Crosses | EUR/GBP, EUR/CHF, AUD/NZD, GBP/CAD | 0.0001 | $10{,}000$ ($10^4$) | 0.00001 ($10^5$) | 0.0100 |
All Yen Pairs (XXX/JPY) | USD/JPY, EUR/JPY, GBP/JPY, AUD/JPY | ¥0.01 | $100$ ($10^2$) | ¥0.001 ($10^3$) | ¥1.00 (1 Yen) |
| High-Unit EM / CEEMEA | EUR/HUF (~400), USD/THB (~34), USD/CZK (~23) | 0.01 or 0.001 | $100$ or $1{,}000$ | 0.001 / 0.0001 | 1.00 / 0.10 |
| Asian Zero-Decimal NDFs | USD/KRW (~1,380), USD/IDR (~15,800), USD/CLP (~950) | 0.01 / 1.00 | $100$ or $1$ | 0.01 | 1.00 / 100 |
Cross-Rate Consistency (EUR/JPY = EUR/USD × USD/JPY) & Position Sizing#
Look at the fourth KPI above (F_EURJPY = F_EURUSD * F_USDJPY): in our worked audit, $1.106995 \times 147.5036 = \mathbf{163.2857}$, which is -376.4 pips (163.286 - 167.050) on EUR/JPY—see full no-arbitrage bounds in cross-rate triangular FX forward arbitrage! Pair pip normalization with FX carry-to-volatility ratio math, size fractional leverage in our Kelly criterion calculator, and browse the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Why does USD/JPY define 1 pip as 0.01 instead of 0.0001 like EUR/USD?
Under the Bretton Woods system USD/JPY was pegged at 360 yen per dollar, and today trades around 140–160 yen per dollar—roughly 100x the numerical unit of 1 USD or 1 EUR. Placing the pip at 0.01 JPY keeps 1 pip roughly equal to ~0.65 bps of notional value, comparable to 1 pip on EUR/USD (~0.92 bps).
What is the difference between a "pip", a "pipette" (point), and a "big figure" in institutional FX?
On EUR/USD (1.08543), the 2nd decimal (1.08) is the "big figure", the 4th decimal (0.0004) is 4 pips, and the 5th decimal (0.00003) is 3 pipettes (tenths of a pip). On USD/JPY (154.236), 154 is the big figure, .23 is 23 pips, and .006 is 6 pipettes!
Why do MT4 and MT5 terminals display 10x larger swap point numbers than Bloomberg FXFA?
5-digit/3-digit MetaTrader servers define one "Point" (_Point) as the minimum tick increment—the 5th decimal (0.00001) on EUR/USD and 3rd decimal (0.001) on USD/JPY (i.e. pipettes)—so +1.85 interbank pips displays as +18.5 MetaTrader points.
How do you convert daily overnight swap points into an annualized percentage interest cost?
Divide the decimal swap points (Pips / M_pip) by the Spot rate S, multiply by (365 / exact settlement days elapsed—remembering Wednesday Tom-Next rolls 3 weekend days!), and multiply by 100 for annualized percent.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). JPY 100 Pip Multiplier vs 10,000 Four-Decimal FX Forward Points Math. QuantCalc Tools. https://quantcalctools.com/guides/jpy-100-pip-multiplier-vs-10000-four-decimal-fx-forward-pointsRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge MathCovered Interest Parity Forwards
Overnight (O/N), Tom-Next (T/N) & Spot-Next (S/N) T+2 FX Roll MathCovered Interest Parity Forwards
Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink MathCovered Interest Parity Forwards
Quarter-End & Year-End G-SIB Window-Dressing FX Swap Turn Premium MathCovered Interest Parity Forwards
SOFR, ESTR & SONIA OIS Compounded In-Arrears FX Forward Discounting MathCovered Interest Parity Forwards
FX Carry-to-Volatility Ratio, Forward Discount Puzzle & Breakeven Spot MathCovered Interest Parity Forwards
Non-Deliverable Forward (NDF) Cash Settlement & Implied Offshore Yield MathCagr Irr Drawdown Compounding
XIRR Newton-Raphson Convergence, Descartes Multiple Roots & MIRR MathCagr Irr Drawdown Compounding
Asymmetric Drawdown Recovery Hyperbola & Breakeven Compounding Time MathCagr Irr Drawdown Compounding
Sharpe Ratio IID Annualization Trap & Lo (2002) Autocorrelation HaircutCagr Irr Drawdown Compounding
Sortino Ratio & Target Downside Semi-Deviation (MAR): Exact LPM2 Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.