
Fisher Exact Real CAGR, Inflation & Annual Tax Drag Compounding Math
Taxing nominal returns in an inflationary regime levies a stealth wealth tax even when real returns are zero; master Fisher exact real CAGR and deferred vs annual turnover tax drag math.
Nominal pre-tax CAGRs flatter long-horizon wealth projections twice over: first, subtracting inflation linearly ($r_{\text{nom}} - \pi$) overstates real compounding during high-inflation decades; second—and far more destructively—governments levy income and capital-gains taxes on NOMINAL dollar gains, NOT inflation-adjusted real gains! When SOFR cash yields $5.00\%$, CPI inflation runs at $3.50\%$, and a top-bracket investor pays $40\%$ marginal income tax, after-tax nominal return is $5.00\%(1 - 0.40) = 3.00\%$, yielding a NEGATIVE real after-tax CAGR of $(1.030 / 1.035) - 1 = -0.48\%$ per year (an effective $133\%$ tax rate on real pre-tax income!). Model nominal baselines in our CAGR Calculator and SOFR Carry Calculator, and explore our CAGR, IRR & Drawdown Hub.
Irving Fisher's Exact Real Return & The Tax-Deferral Compounding Advantage#
Distinguish sharply between Annually Taxed Accrual (taxable interest, non-qualified dividends, or $100\%$ annual turnover short-term trading taxed at rate $\taua$ every year) and Deferred Terminal Realization (buy-and-hold equity or accumulating ETF taxed only ONCE at horizon $T$ at rate $\tau{cg}$ on cumulative gain). Deferring realization lets the government's unpaid tax liability stay inside your account compounding for you free of interest across $T$ years—an advantage that grows nonlinearly with horizon $T$ and return $g$:
- 1. Fisher Exact Real Pre-Tax CAGR : 1 + greal = (1 + gnom) / (1 + pi) => greal = (gnom - pi) / (1 + pi)
- (Note: Linear approximation gnom - pi overstates real CAGR by (gnom - pi) * [pi / (1 + pi)]!)
- 2. Annually Taxed Real CAGR : greal,anntax = [ 1 + gnom * (1 - taua) ] / (1 + pi) - 1
- 3. Deferred Buy-&-Hold Terminal After-Tax Real Wealth (100% Unrealized until Year T, Initial Cost Basis = 1):
- Wnom,aftertax(T) = (1 + gnom)^T * (1 - taucg) + tau_cg
- greal,deferred(T) = [ ( (1 + gnom)^T * (1 - taucg) + taucg )^(1 / T) ] / (1 + pi) - 1
- Effective Annualized Tax Rate of Deferral: taueff(T) = 1 - [ gnom,deferred(T) / g_nom ] (Shrinks toward 0 as T -> inf!)
- Worked 25-Year Taxable Wealth Audit ($1,000,000 Initial Capital, g_nom = +10.00%, Inflation pi = 3.00%):
- Pre-Tax Real Purchasing Power : $1.0M * (1.10 / 1.03)^25 = $1.0M * (1.06796)^25 = $5,176,190 (+6.80% Real CAGR)
- 1. Active 100%-Turnover Trader (Taxed Annually at taua = 37% short-term rate -> gafter = 6.30%):
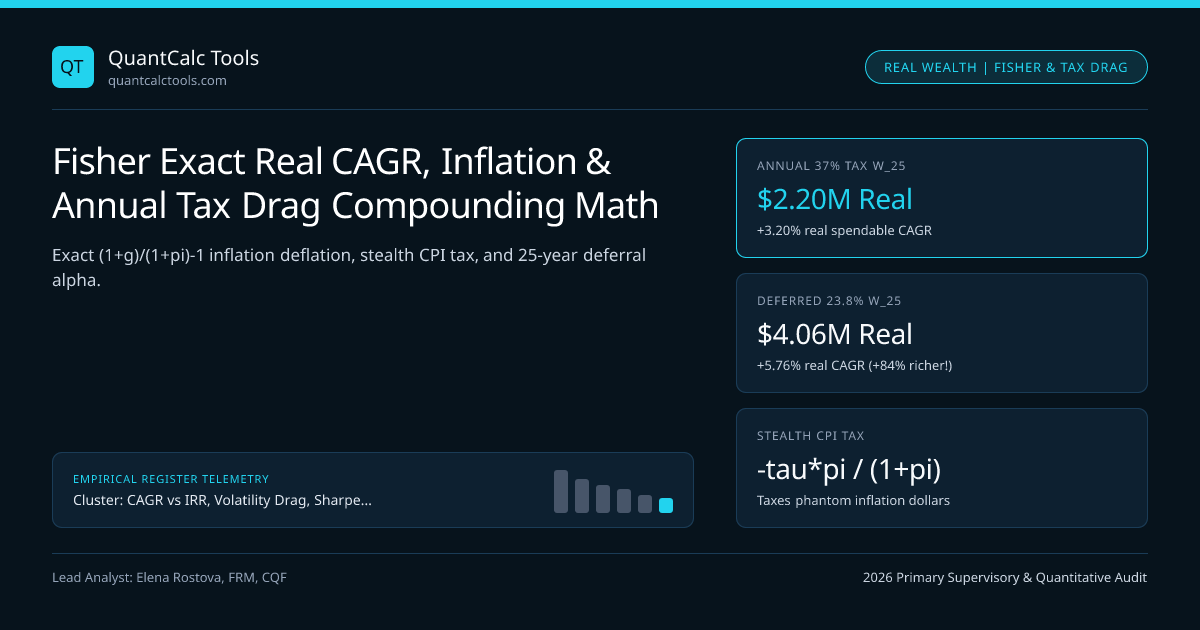
- Real After-Tax CAGR = (1.0630 / 1.0300) - 1 = +3.204% / yr -> Real 25y Purchasing Power = $2,199,790!
- 2. Deferred Buy-&-Hold Investor (Taxed ONCE at Year 25 at tau_cg = 23.8% -> Nominal = 10.8347*(0.762) + 0.238 = $8.494M):
- Nominal After-Tax CAGR = (8.4940)^(1/25) - 1 = +8.932% (Effective annual tax rate just 10.68%, NOT 23.8%!)
- Real After-Tax CAGR = (1.08932 / 1.0300) - 1 = +5.759% / yr -> Real 25y Purchasing Power = $4,055,640!
- Tax-Deferral & Rate Alpha = +$1,855,850 IN REAL TODAY'S DOLLARS (+84.4% richer from exact same +10.0% gross return!)
Look at Step 2's effective tax rate: even though the buy-and-hold investor pays a 23.8% statutory capital-gains rate at Year 25, their effective annualized CAGR drag is only 10.68% of g_nom (10.00% -> 8.93%, just -107 bps/yr instead of -238 bps/yr)! Why? Because the unpaid taxes from Years 1–24 compounded alongside principal for a quarter century!
Portfolio Turnover Velocity: WhyJust 25% Annual Turnover Destroys Deferral Alpha!#
You do NOT have to turn over 100% of your portfolio every year to lose most of the tax-deferral miracle! Horan, Lawton & Racicot (CFA Private Wealth) showed that the marginal tax drag of portfolio turnover is steepest between 0% and 25% annual turnover: moving from 0% turnover (pure buy-and-hold) to just 25% annual turnover already forfeits over $60\%$ of the 25-year tax-deferral benefit because unrealized gains are harvested every 4 years on average instead of compounding for 25 years!
25-Year Real Purchasing-Power Matrix by Tax Wrapper & Portfolio Turnover#
Compare terminal real spendable wealth on $$1\text{M}$ across tax-exempt accounts, buy-and-hold deferral, and active annual taxation:
| Account / Turnover Regime ($g_{\text{nom}} = 10\%$, $\pi = 3\%$, 25y) | Statutory Tax Rate | Effective Annual Tax Drag | Nominal After-Tax CAGR | Exact Fisher Real CAGR | 25y Real Wealth ($$1\text{M}$) |
|---|---|---|---|---|---|
| Tax-Advantaged Wrapper (UK ISA / SIPP / Roth) | $0.0\%$ | $0\text{ bps}$ | $10.00\%$ | $+6.80\%$ | $\$5{,}176{,}190$ |
| 0% Turnover Accumulating ETF (23.8% LTCG) | $23.8\%$ (Yr 25) | $-107\text{ bps}$ | $8.93\%$ | $+5.76\%$ | $\$4{,}055{,}640$ |
| 25% Annual Turnover Stock Fund (23.8% LTCG) | $23.8\%$ (Partial) | $-194\text{ bps}$ | $8.06\%$ | $+4.91\%$ | $\$3{,}316{,}820$ |
| 100% Turnover Quant Pod (23.8% 60/40 Sec 1256) | $26.8\%$ (Annual) | $-268\text{ bps}$ | $7.32\%$ | $+4.19\%$ | $\$2{,}790{,}950$ |
| 100% Short-Term Active / Bond Interest (37%+3.8%) | $40.8\%$ (Annual) | $-408\text{ bps}$ | $5.92\%$ | $+2.83\%$ | $\$2{,}011{,}360$ |
The Stealth Inflation Tax Formula: Why $6\%$ Inflation Doubles Effective Real Tax Rates!#
Decompose nominal return $1 + g{\text{nom}} = (1 + g{\text{real}})(1 + \pi) = 1 + g{\text{real}} + \pi + g{\text{real}}\pi$. When annual tax $\taua$ hits nominal gain $g{\text{nom}}$, you pay $\taua \cdot \pi$ in cold cash strictly on phantom inflation compensation: $$g{\text{real, after-tax}} = g{\text{real}}(1 - \taua) - \frac{\taua \cdot \pi}{1 + \pi}$$ Notice that stealth tax term $-\frac{\taua \pi}{1 + \pi}$: at $\tau_a = 40\%$ and $\pi = 6.0\%$ inflation, inflation taxation alone confiscates $-226\text{ bps}$ per year of real purchasing power even before taxing a single cent of real return!
Asset Location & Tax-Aware Rebalancing Rules#
Locate high-turnover, ordinary-income strategies (credit, hedge funds, and frequent rebalancing pods) inside tax-exempt pensions, ISAs, or institutional wrappers (broker lookup), reserve taxable accounts for low-turnover equity compounding and systematic tax-loss harvesting, check sequence-of-returns real withdrawal math, and review investor protection rules under the UK FCA and FSCS.
Frequently asked questions
When does the simple linear approximation r_real ~= r_nom - inflation become dangerously inaccurate?
Whenever inflation exceeds 4%–5% or nominal returns are high! For example, in an emerging market or 1970s stagflation regime with +18.0% nominal return and +12.0% inflation, naive subtraction claims +6.00% real CAGR, whereas exact Fisher (1.18 / 1.12) - 1 = +5.36%—overstating 20-year real wealth by +13.0%!
Why do Treasury Inflation-Protected Securities (TIPS) suffer "phantom tax" in taxable US accounts?
In the US, annual CPI principal upward adjustments on individual TIPS are taxed as ordinary federal income in the year accrued EVEN THOUGH you receive zero cash principal until maturity! Holding TIPS inside tax-deferred/tax-exempt accounts (or via distributing ETFs) avoids out-of-pocket cash tax bleed.
Why do Ireland-domiciled Accumulating UCITS ETFs compound faster than Distributing ETFs for many non-US investors?
Under Central Bank of Ireland UCITS rules, an Accumulating share class automatically reinvests net dividends internally inside the fund NAV without triggering an immediate personal dividend-distribution tax event in jurisdictions that tax distributions upon receipt but defer capital gains until share sale.
Does tax-loss harvesting permanently eliminate taxes or just defer them by lowering cost basis?
Both! Realizing a -$50,000 loss today to offset high-taxed gains and immediately buying a correlated non-identical replacement ETF resets your cost basis lower, creating an interest-free tax-deferral loan for 20+ years (and if held until step-up at death or charitable donation, eliminates the tax permanently!).
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). Fisher Exact Real CAGR, Inflation & Annual Tax Drag Compounding Math. QuantCalc Tools. https://quantcalctools.com/guides/fisher-exact-real-cagr-inflation-tax-drag-wealth-compounding-mathRelated Cagr Irr Drawdown Compounding & Institutional Briefings
Explore Cagr Irr Drawdown Compounding Hub (20) →Cagr Irr Drawdown Compounding
CAGR vs IRR, Volatility Drag, Sharpe/Sortino & Drawdown Recovery: 2026 GuideCagr Irr Drawdown Compounding
Arithmetic vs Geometric Mean Return: 0.5*Sigma^2 Variance Drain DerivationCagr Irr Drawdown Compounding
TWRR (CAGR) vs MWRR (XIRR): Irregular Cashflow Timing Divergence MathCagr Irr Drawdown Compounding
XIRR Newton-Raphson Convergence, Descartes Multiple Roots & MIRR MathCagr Irr Drawdown Compounding
Asymmetric Drawdown Recovery Hyperbola & Breakeven Compounding Time MathCagr Irr Drawdown Compounding
Sharpe Ratio IID Annualization Trap & Lo (2002) Autocorrelation HaircutCagr Irr Drawdown Compounding
Sortino Ratio & Target Downside Semi-Deviation (MAR): Exact LPM2 MathCagr Irr Drawdown Compounding
Calmar, Sterling & Ulcer Performance Index: Path-Dependent Drawdown MathMarket Insights
Cboe Global Markets (CBOE) Earnings Strength Keeps Valuation Debate In Focus - Yahoo FinanceRegulatory Compliance
Financial Stability Board to launch hedge fund leverage data consultation - Traders UnionMarket Insights
Rayonier jumped after earnings. Why we still see upside for the timber REITMarket Insights
10-year Treasury yield jumps back above 5% as oil gains and more Fed rate hikes expected
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.