
Cheapest-to-Deliver (CTD) Treasury Futures Conversion Factor & DV01 Math
CME 10-Year Note futures do not track a fictitious 6% coupon bond; exact futures DV01 equals the Cheapest-to-Deliver cash Treasury dirty DV01 divided by its 6%-yield Conversion Factor.
Every CME US Treasury futures contract (TU, FV, TY, TN, US, UB) grants the short seller physical delivery choice across a basket of eligible US Treasury notes or bonds, invoicing each deliverable CUSIP at $\text{Invoice Clean Price} = Q{fut} \times CFi$. Because CME Conversion Factors ($CF_i$) discount every deliverable bond's remaining cashflows at a standardized $6.00\%$ semiannual yield, hedging a cash corporate or sovereign bond book with Treasury futures requires dividing the Cheapest-to-Deliver (CTD) bond's dirty DV01 by $CF_{CTD}$! Cross-reference initial margin offsets under CME SPAN 2 Historical/Stress VaR and review baseline sensitivity formulas in our Modified Duration, Convexity & DV01 master guide.
Exact Implied Repo Rate (IRR), Gross Basis, and Futures DV01 Scaling#
For each eligible deliverable Treasury $i$ with spot clean price $Pi$, accrued interest $AI{0,i}$, delivery-date accrued $AI{T,i}$, and Conversion Factor $CFi$:
- Gross Basis: $\text{Gross Basis}i = Pi - Q{fut} \cdot CFi$ (measured in points or 32nds of par).
- Implied Repo Rate ($IRR_i$): The exact annualized ACT/360 money-market return earned by buying cash bond $i$ dirty today and delivering it into short $CF_i$ futures contracts at delivery $T$ (assuming no interim coupon):
$$IRRi = \left( \frac{Q{fut} \cdot CFi + AI{T,i}}{Pi + AI{0,i}} - 1 \right) \times \frac{360}{d}$$
- CTD Identification & Futures DV01: Rational short sellers deliver whichever CUSIP maximizes Implied Repo Rate ($\maxi IRRi$, equivalently minimizing Net Basis = Gross Basis $-$ Carry, known as BNOC). Holding Basis Net of Carry near zero prior to delivery ($P{CTD} \approx Q{fut} \cdot CF{CTD} + \text{Carry}$), differentiating with respect to yield $y{CTD}$ yields the fundamental Futures DV01 & Hedge Ratio equations:
$$DV01{fut} = \frac{DV01{CTD}^{\text{dirty}}}{CF{CTD}} \times \left(1 + r{repo}\frac{d}{360}\right)^{-1} \approx \frac{DV01{CTD}^{\text{dirty}}}{CF{CTD}}, \qquad N{\text{contracts}} = \frac{DV01{\text{portfolio}}}{DV01_{fut} \text{ per contract}}$$
Worked CME 10-Year Note (TY) CTD Selection & $50M Corporate Bond Hedge#
- Deliverable Basket: Remaining maturity 6Y 6M to 7Y 9M (Classic TY basket; Term Repo r_repo = 4.35%, d = 62 days)
- Quoted TY Futures Price Q_fut = 110-16 (110.5000 decimal); Prevailing 7Y Treasury YTM = 4.25% (< 6% CF standard!)
- Candidate A (Short-Duration Low-Coupon 3.875% 6.65Y Note):
- Spot Clean PA = 97.7656, AI0 = 0.85, AIT = 1.51, Conversion Factor CFA = 0.8842
- Gross Basis_A = 97.7656 - (110.5000 * 0.8842) = 97.7656 - 97.7041 = +0.0615 pts (~2.0 / 32nds!)
- Implied Repo_A = [ (97.7041 + 1.51) / (97.7656 + 0.85) - 1 ] * (360 / 62) = +4.12% (HIGHEST -> CTD!)
- Candidate B (Long-Duration High-Coupon 4.625% 7.70Y Note):
- Spot Clean PB = 102.4219, AI0 = 1.02, AIT = 1.80, Conversion Factor CFB = 0.9168
- Gross Basis_B = 102.4219 - (110.5000 * 0.9168) = 102.4219 - 101.3064 = +1.1155 pts (35.7 / 32nds -> Expensive!)
- Exact TY Futures DV01 & Contract Count to Hedge $50,000,000 Corporate Portfolio (DV01_port = $39,800/bp):
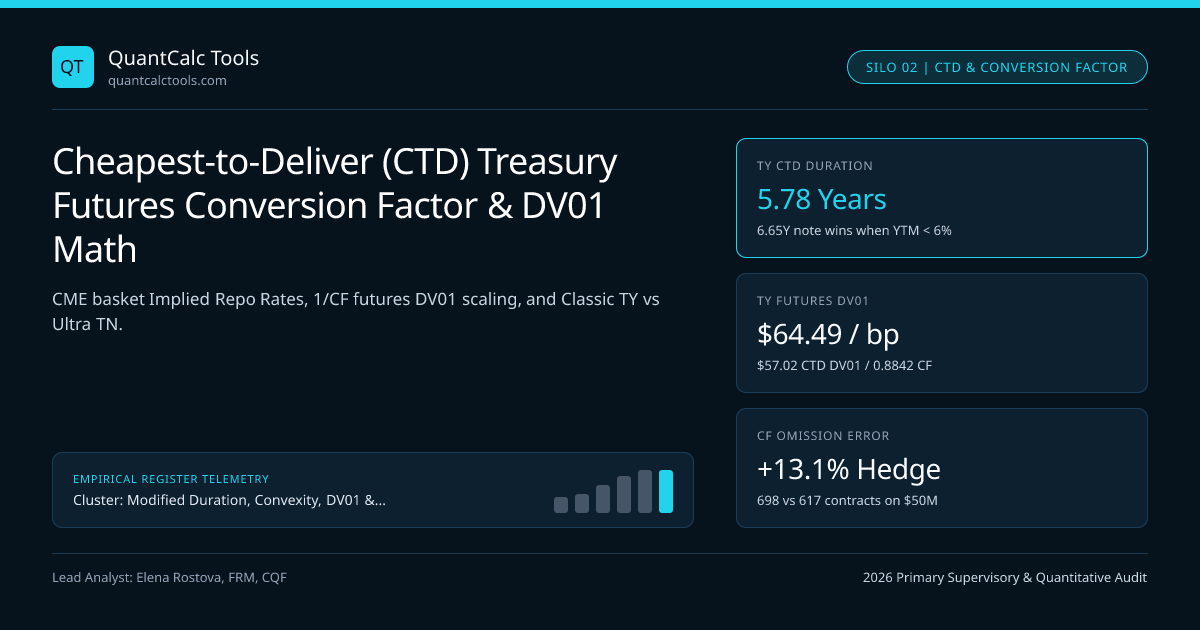
- CTD Dirty Price = 97.7656 + 0.8500 = 98.6156; CTD Modified Duration D_mod = 5.7820 yrs
- CTD Dirty DV01 per $100,000 face = $98,615.60 * 5.7820 * 0.0001 = $57.0195 / bp
- TY Futures DV01 per Contract = $57.0195 / 0.8842 = $64.4871 / bp per contract!
- Required Short TY Contracts = $39,800 / $64.4871 = 617.18 => Short 617 TY Contracts!
- (Ignoring CF_A = 0.8842 would compute $39,800 / $57.02 = 698 contracts -> +13.1% OVER-HEDGED ERROR!)
Look at the final check: forgetting to divide by $CF_A = 0.8842$ leads an uncalibrated trader to short 698 contracts instead of 617—over-hedging by 81 contracts ($+$5,223/\text{bp}$)! And notice why the classic TY contract has an effective duration of $5.78$ years rather than 10 years: CME's TY deliverable basket spans $6.5$ to $10$ years, and when market yields ($4.25\%$) sit below $6.00\%$, low-coupon shortest-maturity $6.65$-year notes always dominate CTD! (Desks wanting true 9.5–10Y duration use CME Ultra 10-Year TN futures!)
The 6.00% Yield Inflection & Embedded Short Delivery Quality Option#
Why does CTD jump violently if Treasury yields surge past $6.00\%$?
- Yields $< 6.00\%$: Discounting at $6\%$ undervalues long-duration bonds more than short-duration bonds relative to $4.25\%$ market prices, making the lowest-duration bond Cheapest-to-Deliver.
- Yields $> 6.00\%$: Discounting at $6\%$ overvalues long-duration bonds relative to $6.50\%$ market prices, flipping CTD instantaneously to the longest-duration bond in the basket!
Because the short futures trader holds this free Quality / Switch Option (plus End-of-Month timing and Wildcard options), Treasury futures exhibit negative convexity right around $y \approx 6.00\%$ or steep curve switch boundaries—stretching futures duration when yields rise and contracting duration when yields fall, just like callable debt! Model repo funding breakevens via Leveraged Treasury Repo Carry & Rolldown and our SOFR compounding & carry calculator.
CME US Treasury Futures Suite: Deliverable Baskets & Typical DV01 Reference#
| CME Futures Ticker & Name | Face Value | Deliverable Maturity Window | Typical CTD Duration ($y < 6\%$) | Typical Contract DV01 ($/bp) |
|---|---|---|---|---|
ZT / TU (2-Year T-Note) | $$200,000$ | $1\text{Y } 9\text{M}$ to $2\text{Y } 0\text{M}$ | $1.75\text{ yrs}$ | $\approx \$36.80 / \text{bp}$ |
ZF / FV (5-Year T-Note) | $$100,000$ | $4\text{Y } 2\text{M}$ to $5\text{Y } 3\text{M}$ | $3.85\text{ yrs}$ | $\approx \$42.90 / \text{bp}$ |
ZN / TY (Classic 10-Year) | $$100,000$ | $6\text{Y } 6\text{M}$ to $7\text{Y } 9\text{M}$ (or $10\text{Y}$) | $5.78\text{ yrs}$ (Belly!) | $\approx \$64.49 / \text{bp}$ |
TN (Ultra 10-Year T-Note) | $$100,000$ | $9\text{Y } 5\text{M}$ to $10\text{Y } 0\text{M}$ | $7.85\text{ yrs}$ (True 10Y!) | $\approx \$84.20 / \text{bp}$ |
ZB / US (Classic T-Bond) | $$100,000$ | $15\text{Y } 0\text{M}$ to $25\text{Y } 0\text{M}$ | $11.60\text{ yrs}$ | $\approx \$122.50 / \text{bp}$ |
UB (Ultra T-Bond) | $$100,000$ | $25\text{Y } 0\text{M}$ to $30\text{Y } 0\text{M}$ | $16.90\text{ yrs}$ | $\approx \$186.40 / \text{bp}$ |
Dirty Scaling, Calendar Rolls & Institutional Cross-Hedging#
Always verify dirty CTD prices before quarterly Mar/Jun/Sep/Dec delivery rolls using DV01 clean vs dirty bond price scaling and audit repo financing spreads in leveraged Treasury repo carry and rolldown math. Execution platforms supporting direct CME FIX order routing are profiled under FIX API software infrastructure, with full curriculum navigation on the Modified Duration & Key-Rate Hedging Topic Hub.
Frequently asked questions
Why does CME still use a 6.00% yield standard for Treasury futures Conversion Factors?
Standardizing Conversion Factors at 6.00% semiannual yield creates stable, deterministic invoice multipliers known at contract listing. Changing the standard mid-cycle would alter CTD biases and disrupt historical basis and calendar-spread relationships.
Why do Classic 10-Year Treasury futures (ZN/TY) hedge like a 6.7-year bond instead of a 10-year bond?
CME’s Classic TY contract allows delivery of Treasury notes with 6.5 to 10 years remaining maturity. Whenever market yields are below the 6% CF discount rate, the shortest-duration 6.5-to-7-year note has the lowest Net Basis and becomes CTD.
Why is the 2-Year Treasury Note contract (ZT/TU) $200,000 face value while 5Y, 10Y, and 30Y are $100,000?
Because a 2-year note has a Modified Duration under 1.9 years, a $100,000 contract would carry only ~$18/bp of DV01, inflating per-DV01 exchange fees and tick granularity. Doubling ZT face value to $200,000 lifts contract DV01 to ~$36.80/bp.
What does a negative Net Basis (BNOC < 0) on the Cheapest-to-Deliver Treasury mean?
Theoretical BNOC equals the value of the short’s embedded delivery options (Quality, Timing, and Wildcard options) and is normally >= 0. A negative BNOC signals an arbitrage opportunity (buy cash CTD, short futures, deliver) unless constrained by balance-sheet costs.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). Cheapest-to-Deliver (CTD) Treasury Futures Conversion Factor & DV01 Math. QuantCalc Tools. https://quantcalctools.com/guides/cheapest-to-deliver-ctd-treasury-futures-conversion-factor-dv01Related Bond Duration Convexity Math & Institutional Briefings
Explore Bond Duration Convexity Math Hub (20) →Bond Duration Convexity Math
Modified Duration, Convexity, DV01 & Key-Rate Hedging: 2026 Quantitative GuideBond Duration Convexity Math
Leveraged Treasury Repo Carry, Curve Rolldown & Breakeven Yield Spike MathBond Duration Convexity Math
Redington Liability Immunization: Duration Matching & Convexity Dispersion MathBond Duration Convexity Math
Zero-Coupon STRIPS Convexity Scaling: Quadratic Maturity Leverage MathBond Duration Convexity Math
Par Swap DV01 vs Zero-Rate PV01: Jacobian Curve Transformation MathBond Duration Convexity Math
ACT/ACT ICMA vs 30/360 Accrued Interest & Odd-Stub Duration Bias MathBond Duration Convexity Math
TIPS Real-Yield Duration vs Nominal Treasury Empirical Beta Hedging MathBond Duration Convexity Math
Spread Duration vs Duration-Times-Spread (DTS): Credit Hedging MathCovered Interest Parity Forwards
Non-Deliverable Forward (NDF) Cash Settlement & Implied Offshore Yield MathCovered Interest Parity Forwards
Historic-Rate vs Market-Rate FX Swaps: Uneven Notional & NPV Tail MathCovered Interest Parity Forwards
Cross-Rate Triangular FX Forward Arbitrage & Bid-Ask Swap Bounds MathCovered Interest Parity Forwards
Continuous Garman-Kohlhagen vs Discrete Money-Market CIP FX Options Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.