
Covered Interest Parity Forwards
ACT/360 vs ACT/365 FX Forward Day-Count Mismatch: GBP/USD & USD/CAD Math
Even when UK SONIA and US SOFR print the exact same 4.50% nominal rate, GBP/USD trades at a +7.9-pip 1-year forward premium because USD accrues 365/360 (+1.39%) more interest per calendar year.
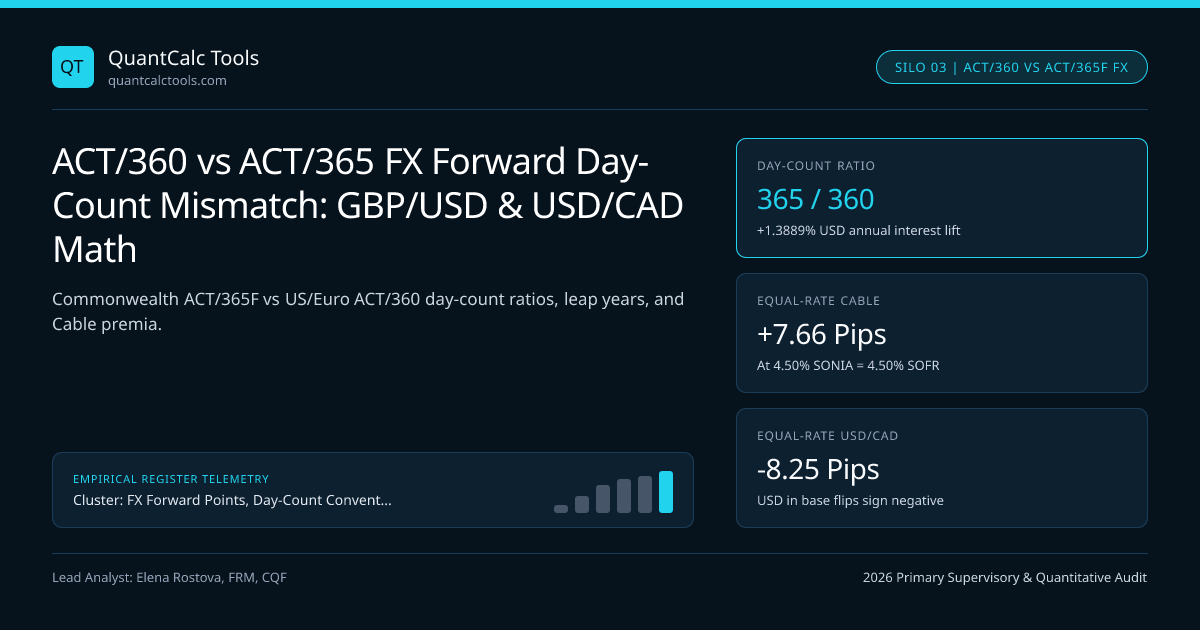
Here is a classic interbank FX trading floor riddle: suppose US 1-year NY Fed SOFR Index OIS equals $4.500\%$, UK 1-year SONIA OIS equals $4.500\%$, cross-currency basis is strictly $0.0\text{ bps}$, and spot GBP/USD is $1.28000$. Are 1-year GBP/USD forward points equal to zero?! No—1-year GBP/USD trades at $+7.65$ pips ($1.280765$)! Why? Because British Sterling (alongside CAD, AUD, NZD, HKD, SGD, JPY, and PLN) accrues money-market interest on ACT/365 Fixed, whereas the US Dollar (alongside EUR, CHF, SEK, NOK, and MXN) accrues on ACT/360! Test live day-count pairs in our FX forward points & carry calculator and anchor full parity rules in our Covered Interest Parity & FX Forward Points master guide.
Exact Equal-Nominal-Rate Asymmetry Proof ($365/360 = 1.013889$)#
Substitute identical nominal rate $r{\text{USD}} = r{\text{GBP}} = r$ across a $d = 365$-day non-leap calendar year into Covered Interest Parity (CIP): $$F_{\text{GBP/USD}}(365) = S \times \frac{1 + r \cdot \dfrac{365}{360}}{1 + r \cdot \dfrac{365}{365}} = S \times \frac{1 + 1.013889\,r}{1 + r} = S\left(1 + \frac{\frac{5}{360}\,r}{1 + r}\right) > S!$$ Look at that numerator: over $365$ calendar days, a $4.500\%$ ACT/360 USD deposit actually pays $4.500\% \times (365/360) = 4.5625\%$ effective annual interest (+6.25 bps extra cash!), while a $4.500\%$ ACT/365F GBP deposit pays exactly $4.500\%$! Even in a leap year ($d = 366$ days), ACT/365 Fixed (ACT/365F) keeps its denominator locked at $365$ ($366/365 = 1.00274$), while USD's denominator stays $360$ ($366/360 = 1.01667$), preserving the exact $365 : 360$ accrual ratio!
Worked 1-Year GBP/USD & USD/CAD Day-Count Audit ($100M Ticket)#
- 1) Pair A — GBP/USD (GBP = Base [ACT/365F], USD = Quote [ACT/360], Spot S = 1.28000, d = 365 days):
- USD Growth Factor (Quote) = 1 + 0.04500 * (365 / 360) = 1.04562500
- GBP Growth Factor (Base) = 1 + 0.04500 * (365 / 365) = 1.04500000
- Exact Forward Outright F = 1.28000 * (1.04562500 / 1.04500000) = 1.28076555
- Exact Forward Points = (1.28076555 - 1.28000) * 10,000 = +7.66 pips!
- Dollar Value on GBP 100,000,000 Notional = +$76,555 pure day-count cashflow!
- 2) Pair B — USD/CAD (USD = Base [ACT/360], CAD = Quote [ACT/365F], Spot S = 1.38000, d = 365 days):
- Notice USD is now in the DENOMINATOR (Base) while CAD (ACT/365F) is in the NUMERATOR (Quote)!
- CAD Growth Factor (Quote) = 1 + 0.04500 * (365 / 365) = 1.04500000
- USD Growth Factor (Base) = 1 + 0.04500 * (365 / 360) = 1.04562500
- Exact Forward Outright F = 1.38000 * (1.04500000 / 1.04562500) = 1.37917513
- Exact Forward Points = (1.37917513 - 1.38000) * 10,000 = -8.25 pips (FORWARD DISCOUNT!)
- 3) Exact Breakeven SONIA / CORRA Rate Required for Zero Forward Points (F = S) Against 4.500% USD SOFR:
- r365breakeven = r_360 * (365 / 360) = 4.500% * 1.0138889 = 4.5625%! (+6.25 bps higher nominal rate!)
Look at Step 3: UK SONIA or Canadian CORRA must print $+6.25\text{ bps}$ higher than US SOFR ($4.5625\%$ vs $4.5000\%$) just for GBP/USD or USD/CAD swap points to sit at zero! Any quantitative carry screener that ranks currencies by raw $r{\text{foreign}} - r{\text{USD}}$ without multiplying ACT/360 rates by $365/360$ systematically misranks Sterling, Loonie, Aussie, and Kiwi carry by $5\text{ to }8\text{ bps}$!

Leap-Year Trap: Why FX Uses ACT/365 Fixed (Never ACT/ACT ISDA)!#
Watch out for a sneaky Python QuantLib / Excel bug during leap years (2024, 2028): Sterling SONIA, Canadian CORRA, Australian AONIA, and Japanese TONA all use Actual/365 Fixed (ACT/365F)—meaning in a 366-day leap year, the denominator stays 365 (366 / 365 = 1.0027397), NOT 366! Coding ACT/ACT instead of ACT/365F drops 1 day of GBP interest ($1.23\text{ bps}$, or $\sim 1.6$ pips on 1Y Cable) across every leap-year February 29th! Verify compounded SOFR ACT/360 indices in our SOFR overnight compounding & carry calculator.
Global FX Money-Market Day-Count Convention Reference Matrix#
| Currency Group | ISO Currency Codes | Money-Market Basis | Leap-Year Denominator | 365-Day Factor at $r = 5.00\%$ |
|---|---|---|---|---|
| US & Eurozone Core | USD, EUR, CHF | ACT/360 | $360$ (366/360) | $1.050694$ (+6.94 bps uplift!) |
| Nordic & LatAm | SEK, NOK, DKK, MXN | ACT/360 | $360$ (366/360) | $1.050694$ (+6.94 bps uplift!) |
| UK & Commonwealth | GBP, CAD, AUD, NZD | ACT/365 Fixed | $365$ (366/365) | $1.050000$ (Exact nominal) |
| Developed Asia & CEEMEA | JPY, HKD, SGD, ZAR, PLN | ACT/365 Fixed | $365$ (366/365) | $1.050000$ (Exact nominal) |
Brazil Onshore (BRL CDI) | BRL (USD/BRL NDF) | BUS/252 (Compounded!) | $252$ ANBIMA business days | $(1 + r)^{d_{\text{bus}}/252}$ |
Combining Day-Count Rules with T+1 Spot Lags and OIS Discounting#
Notice how USD/CAD combines two non-standard conventions simultaneously: ACT/365F vs ACT/360 day counts AND a T+1 spot settlement lag (explored in USD/CAD T+1 spot lag and Modified Following calendars), while modern interbank curves discount cashflows using compounded RFRs in SOFR, ESTR, and SONIA OIS FX forward discounting. Check UK & Commonwealth dealer disclosures via the British Columbia Securities Commission and browse the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Why do GBP, CAD, AUD, and NZD use ACT/365 while USD and EUR use ACT/360?
Historical British Empire banking law standardized sterling bills of exchange around the 365-day Julian/Gregorian year, a convention inherited across Commonwealth central banks (BoE, BoC, RBA, RBNZ, HKMA, MAS). Continental Lombard and US Federal Reserve markets adopted 360-day merchant banking tables.
Does USD/JPY suffer from the same ACT/360 vs ACT/365 mismatch?
Yes on cash/TONA OIS legs! Bank of Japan TONA OIS accrues on ACT/365 Fixed while USD SOFR accrues on ACT/360. Because JPY interest rates have historically been low (0.0%–0.5%), the 5/360 scaling mostly hits the much larger USD SOFR leg!
How are FX forwards beyond 1 year (> 1Y) calculated when simple money-market interest stops applying?
Beyond 1 year, simple money-market factors (1 + r*d/B) are replaced by exact zero-coupon OIS Discount Factors: F(0, T) = S * [DF_base(0, T) / DF_quote(0, T)] adjusted for spot lag and cross-currency basis swap spreads.
How does Brazil’s BUS/252 convention affect USD/BRL Non-Deliverable Forward pricing?
Brazil’s DI futures curve compounds exponentially strictly on ANBIMA Brazilian banking days: (1 + CDI)^(bd/252), while the offshore USD SOFR discount leg counts all calendar days on ACT/360—requiring exact Brazilian holiday calendars!
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). ACT/360 vs ACT/365 FX Forward Day-Count Mismatch: GBP/USD & USD/CAD Math. QuantCalc Tools. https://quantcalctools.com/guides/act-360-vs-act-365-fx-forward-day-count-mismatch-gbpusd-usdcadRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
JPY 100 Pip Multiplier vs 10,000 Four-Decimal FX Forward Points MathCovered Interest Parity Forwards
Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge MathCovered Interest Parity Forwards
Overnight (O/N), Tom-Next (T/N) & Spot-Next (S/N) T+2 FX Roll MathCovered Interest Parity Forwards
Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink MathCovered Interest Parity Forwards
Quarter-End & Year-End G-SIB Window-Dressing FX Swap Turn Premium MathCovered Interest Parity Forwards
SOFR, ESTR & SONIA OIS Compounded In-Arrears FX Forward Discounting MathCovered Interest Parity Forwards
FX Carry-to-Volatility Ratio, Forward Discount Puzzle & Breakeven Spot MathCagr Irr Drawdown Compounding
TWRR (CAGR) vs MWRR (XIRR): Irregular Cashflow Timing Divergence MathCagr Irr Drawdown Compounding
XIRR Newton-Raphson Convergence, Descartes Multiple Roots & MIRR MathCagr Irr Drawdown Compounding
Asymmetric Drawdown Recovery Hyperbola & Breakeven Compounding Time MathCagr Irr Drawdown Compounding
Sharpe Ratio IID Annualization Trap & Lo (2002) Autocorrelation Haircut
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.