
Covered Interest Parity Forwards
Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge Math
Riskless Covered Interest Parity broke permanently in 2008: persistent negative cross-currency basis wedges (-15 to -45 bps) measure the shadow price of G-SIB balance-sheet leverage and global USD scarcity.
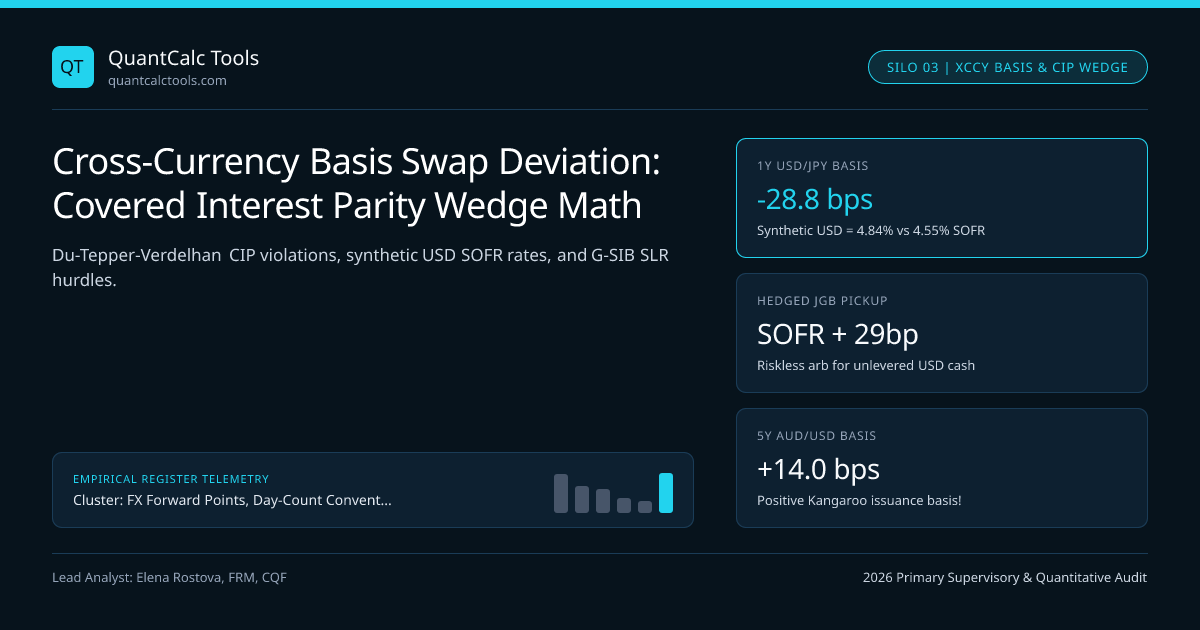
For forty years prior to September 2008, textbook Covered Interest Parity (CIP) was the closest thing to a physical law in economics—holding within $\pm 2\text{ bps}$ across every G10 currency! Yet as documented in the seminal *Du, Tepper & Verdelhan (2018, Journal of Finance)* paper, CIP has violated zero every single trading day since 2008, widening to $-65\text{ bps}$ in peaceful years and blowing out past $-250\text{ bps}$ during March 2020! That persistent wedge is the Cross-Currency Basis ($x_{ccy}$): the extra spread a non-US borrower must pay above NY Fed SOFR Index when raising synthetic US dollars via an FX swap! Test basis-adjusted forwards in our FX forward points & carry calculator and anchor full swap mechanics in our Covered Interest Parity & FX Forward Points master guide.
Exact Definition of FX-Implied USD Rate & Cross-Currency Basis Sign Convention#
Interdealer brokers quote G10 cross-currency basis swaps (EUR/USD, USD/JPY, GBP/USD, AUD/USD) as a basis-point spread $\alpha{\text{basis}}$ added to the NON-USD floating OIS leg (€STR + alpha, TONA + alpha, SONIA + alpha) against flat USD SOFR + 0 bps, with initial and final principal exchanges at spot! Rearranging the discrete CIP equation to solve for the **Synthetic FX-Implied USD Interest Rate ($r{\text{USD}}^{\text{synth}}$) and CIP Basis ($x{ccy}$)**: $$1 + r{\text{USD}}^{\text{synth}}\,\frac{d}{360} = \frac{F}{S}\left(1 + r{\text{foreign}}\,\frac{d}{Bf}\right), \qquad x{ccy} \equiv r{\text{USD}}^{\text{OIS}} - r{\text{USD}}^{\text{synth}} \approx \alpha{\text{basis}}$$ Look at the sign when x_ccy = -25 bps (negative basis):
- Direct Cash USD SOFR $= 4.55\%$, while Synthetic FX-Swap Implied USD Cost $r_{\text{USD}}^{\text{synth}} = 4.55\% - (-0.25\%) = \mathbf{4.80\%}$!
- Equivalently, a European bank willing to lend cash EUR at
€STR - 25 bps($2.40\%$ instead of $2.65\%$) is paying a $25\text{ bps}$ scarcity surcharge to get its hands on scarce US dollars!
Worked $100M Arbitrage Audit: Why G-SIB Leverage Ratios Sustain a -28 bps JPY Basis!#
- Market Quotes (d = 365 Days):
- Spot USD/JPY S = 154.000; Live Market 1Y Forward F_mkt = 147.4600 (-654.00 pips!)
- 1Y USD SOFR OIS = 4.550% (ACT/360 -> 365-day factor = 1 + 0.04550*365/360 = 1.046132)
- 1Y BoJ JGB / TONA OIS = 0.450% (ACT/365F -> 365-day factor = 1.004500)
- 1) Extract Implied Synthetic USD Rate & CIP Cross-Currency Basis:
- (1 + rUSDsynth * 365/360) = (S / Fmkt) * (1 + rJPY) [Note S/F since JPY is quote!]
- = (154.000 / 147.4600) * 1.004500 = 1.044351 * 1.004500 = 1.049051!
- rUSDsynth (ACT/360) = (1.049051 - 1) * (360 / 365) = 4.8379%!
- Cross-Currency Basis xccy = rUSDOIS (4.5500%) - rUSD_synth (4.8379%) = -28.79 bps!
- 2) Riskless Cash Arbitrage Trade for a USD Cash-Rich Investor (Sovereign Wealth Fund / Reserve Manager):
- Swap $100,000,000 USD -> ¥15.40B JPY at Spot 154.000, buy 1Y Japanese T-Bill @ 0.450% (-> ¥15,469.30M),
- simultaneously sell ¥15,469.30M forward @ 147.4600 => Locks in $104,905,059 USD!
- Compare vs 1Y US Treasury/SOFR ($104,613,194) => +$291,865 RISKLESS ARBITRAGE PICKUP (+28.8 bps)!
- 3) Why Don't G-SIB Dealer Banks Arbitrage That +28.8 bps Down to 0 bps?
- Basel III Tier-1 Leverage Ratio (5%–6% G-SIB SLR) requires ~$5.5M Tier-1 equity per $100M balance-sheet asset
- + SA-CCR FX add-on + Wholesale Funding Spread (+18 bps over SOFR for unsecured bank CP)!
- Bank Net Spread = +28.8 bps - 18.0 bps funding = +10.8 bps ($108k) on $5.5M equity => 1.96% ROE (Fails 12% ROE hurdle!)
Step 2 and Step 3 explain the entire post-2008 global funding architecture:
- Leveraged G-SIB banks constrained by Basel III Leverage Ratios (
SLR) and UK PRA / Fed capital surcharges cannot earn their $12\%$ ROE hurdle on a $28.8\text{ bps}$ basis! - Unlevered USD cash holders (US Prime Funds, Sovereign Reserve Managers, Berkshire Hathaway) DO NOT borrow at bank CP spreads or post G-SIB SLR capital—allowing them to buy FX-hedged Japanese T-Bills and earn SOFR + 28.8 bps risk-free!
The Central Bank Swap Line Ceiling & Positive-Basis Currencies (AUD & CAD)!#
Wait—is cross-currency basis always negative against USD? No! Check cross-sectional currency fundamentals:
- Net Foreign Creditors buying USD assets (
JPY,EUR,CHF,TWD): Massive structural demand to borrow USD via FX swaps drives basis strictly negative (-15 to -40 bps)—bounded during panics only by the Federal Reserve's standing Central Bank Liquidity Swap Lines (OIS + 25 bps)! - High-Issuance Commodity / Kangaroo Bond Currencies (
AUD,NZD): Global supranationals issue Kangaroo bonds in AUD and swap proceeds back into USD/EUR, often pushing 5-yearAUD/USDcross-currency basis POSITIVE (+8 to +18 bps)!
Structural Cross-Currency Basis Profile Across Major G10 Pairs (1Y vs 5Y)#
| Currency Pair | Typical 1Y Basis | Typical 5Y XCCY Basis | Dominant Structural Flow Driver | Winner of Basis Wedge |
|---|---|---|---|---|
USD/JPY (TONA vs SOFR) | $-28\text{ bps}$ | $-42\text{ bps}$ | Japanese lifers/banks hedging US credit | USD cash holders buying hedged JGBs |
EUR/USD (€STR vs SOFR) | $-16\text{ bps}$ | $-22\text{ bps}$ | European insurers + Yankee/Reverse Yankee | USD cash holders buying hedged Bunds/OATs |
USD/CHF (SARON vs SOFR) | $-20\text{ bps}$ | $-26\text{ bps}$ | Swiss private wealth & pension USD hedging | USD cash / CHF corporate issuers |
GBP/USD (SONIA vs SOFR) | $-12\text{ bps}$ | $-14\text{ bps}$ | Balanced London financial center two-way flow | Mild USD lender advantage |
AUD/USD (AONIA vs SOFR) | $+6\text{ bps}$ | $+14\text{ bps}$ (Positive!) | Kangaroo bond issuance & Aussie super funds | AUD cash holders / Kangaroo issuers! |
Capital & Sovereign Asset-Swap Applications of the CIP Wedge#
Explore how global bond funds harvest that $-28\text{ bps}$ JPY and $-16\text{ bps}$ EUR wedge directly in currency-hedged foreign sovereign bond yield pickup, how corporate treasurers exploit commercial paper spreads in synthetic USD funding via FX swaps, and how SA-CCR and ISDA SIMM v2.6 drive dealer pricing in SA-CCR and SIMM FX forward margin drag on the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Why is the cross-currency basis convention quoted on the NON-USD leg (e.g. ESTR - 20 bps vs SOFR flat)?
Because USD is the central numeraire of global FX swaps, dealers keep the USD leg clean at flat SOFR + 0 bps so spreads across EUR, JPY, GBP, CHF, and AUD can be compared apples-to-apples on a single basis-point scale.
Does Covered Interest Parity deviation reflect bank credit default risk or balance-sheet scarcity?
Balance-sheet scarcity! Du, Tepper & Verdelhan (2018) proved that big CIP deviations persist even on 100% repo-collateralized Treasury bills and OIS-collateralized swaps with zero credit risk—spiking sharply on regulatory quarter-end reporting dates.
How do Federal Reserve Central Bank Liquidity Swap Lines cap extreme cross-currency basis blowouts?
Through standing swap lines with the ECB, BoJ, BoE, SNB, and BoC, foreign central banks lend actual cash USD to domestic banks at USD OIS + 25 bps against domestic collateral—creating an arbitrage ceiling around -35 to -50 bps once operations settle.
What is a "Reverse Yankee" corporate bond issue and how does the EUR/USD basis drive it?
When EUR/USD 5Y–10Y cross-currency basis is negative alongside tight Euro credit spreads, US blue-chip corporations (Apple, Microsoft) issue EUR-denominated bonds ("Reverse Yankees") and swap EUR proceeds into USD via XCCY swaps cheaper than issuing domestic USD bonds!
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge Math. QuantCalc Tools. https://quantcalctools.com/guides/cross-currency-basis-swap-deviation-covered-interest-parity-wedgeRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
Overnight (O/N), Tom-Next (T/N) & Spot-Next (S/N) T+2 FX Roll MathCovered Interest Parity Forwards
Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink MathCovered Interest Parity Forwards
Quarter-End & Year-End G-SIB Window-Dressing FX Swap Turn Premium MathCovered Interest Parity Forwards
SOFR, ESTR & SONIA OIS Compounded In-Arrears FX Forward Discounting MathCovered Interest Parity Forwards
FX Carry-to-Volatility Ratio, Forward Discount Puzzle & Breakeven Spot MathCovered Interest Parity Forwards
Non-Deliverable Forward (NDF) Cash Settlement & Implied Offshore Yield MathCovered Interest Parity Forwards
Historic-Rate vs Market-Rate FX Swaps: Uneven Notional & NPV Tail MathCagr Irr Drawdown Compounding
Asymmetric Drawdown Recovery Hyperbola & Breakeven Compounding Time MathCagr Irr Drawdown Compounding
Sharpe Ratio IID Annualization Trap & Lo (2002) Autocorrelation HaircutCagr Irr Drawdown Compounding
Sortino Ratio & Target Downside Semi-Deviation (MAR): Exact LPM2 MathCagr Irr Drawdown Compounding
Calmar, Sterling & Ulcer Performance Index: Path-Dependent Drawdown Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.