
Covered Interest Parity Forwards
Synthetic USD Commercial Paper Funding: FX Swap Implied SOFR Spread Math
Multinational corporate and bank treasurers arbitrage global money markets daily by issuing 90-day Euro or Sterling Commercial Paper and swapping proceeds into synthetic US dollars below direct USCP spreads.
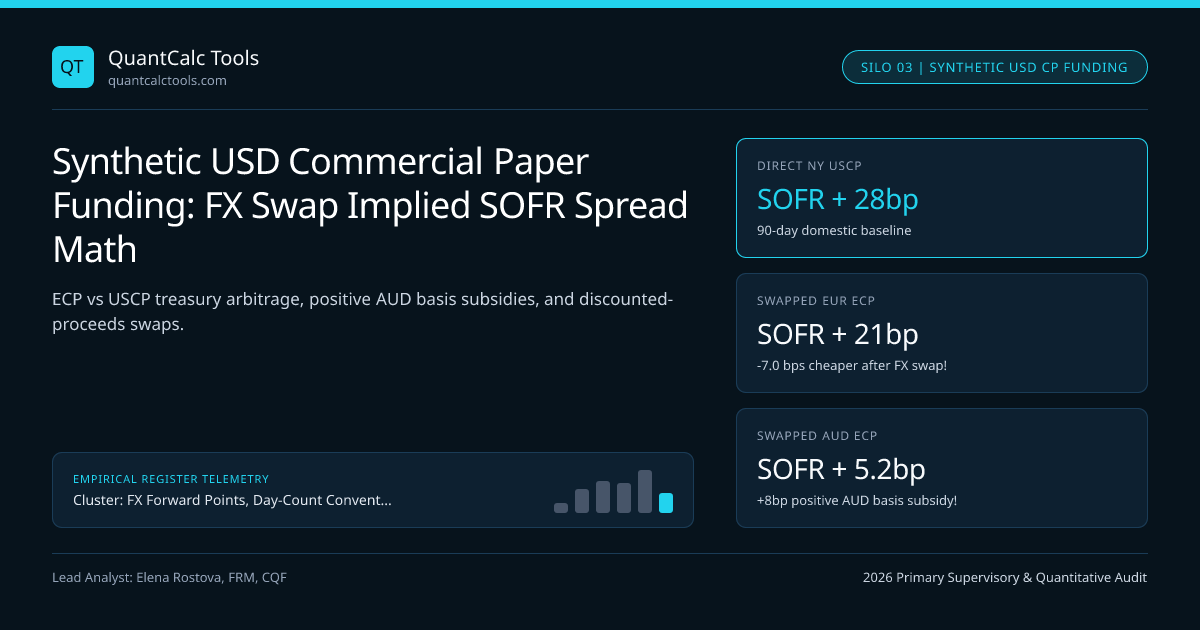
Every morning at 08:30 London time, A1/P1 corporate and bank funding desks run an FX-Swapped Commercial Paper (ECP / USCP) Funding Matrix: is it cheaper today to raise $$250,000,000$ of 90-day cash by issuing direct US Commercial Paper (USCP) in New York at SOFR + 28 bps, OR by issuing Euro Commercial Paper (ECP) in EUR, GBP, or CHF in London and simultaneously executing a Buy-USD-Spot / Sell-USD-Forward FX Swap?! When European money-market funds are flush with cash and bid corporate EUR spreads tight (€STR + 8 bps) while the EUR/USD FX swap basis sits at a mild -12 bps, synthetic FX-swapped USD funding beats direct USCP by -8 bps ($50,000 saved per quarter on $250M)! Run quick swap conversions in our FX forward points & carry calculator and anchor full parity rules in our Covered Interest Parity & FX Forward Points master guide.
Exact All-In Synthetic USD Funding Formula (Including Dealer Spreads & Day Counts!)#
Suppose a corporate treasurer issues discounted/interest-bearing Foreign Commercial Paper in currency $f$ (say EUR on ACT/360 or GBP on ACT/365F) at all-in yield $rf^{\text{CP}}$ for $d$ days, converts foreign proceeds into USD at **Spot Bid $S{\text{Bid}}$ (if EUR/USD) and locks in repayment of principal + CP interest at Forward Ask $F{\text{Ask}} = S{\text{Bid}} + \text{Points}{\text{Ask}}$! The exact All-In ACT/360 Synthetic USD Rate ($r{\text{USD}}^{\text{all-in}}$) and Spread to NY Fed SOFR equal: $$1 + r{\text{USD}}^{\text{all-in}}\,\frac{d}{360} = \left(\frac{S{\text{ref}} + \text{Points}{\text{Ask}}}{S{\text{ref}}}\right)\left(1 + rf^{\text{CP}}\,\frac{d}{Bf}\right) \implies s{\text{synth}} \approx sf^{\text{CP}} - x{ccy} + \text{Swap Spread}{\text{bps}}$$ Look at that crystal-clear 3-Term Approximation** ($s{\text{synth}} \approx sf^{\text{CP}} - x{ccy} + \text{Cost}{\text{bid-ask}}$):
- If foreign CP credit spread $sf^{\text{CP}} = +8\text{ bps}$ (over
€STR), cross-currency basis $x{ccy} = -12\text{ bps}$ (adds $+12\text{ bps}$ cost because basis is negative!), and FX swap bid-ask is $+0.8\text{ bps}$, then All-In Synthetic USD Cost =SOFR + 8 + 12 + 0.8 = SOFR + 20.8 bps—beating directUSCPatSOFR + 28 bpsby7.2 bps!
Worked $250M 90-Day Multi-Currency Commercial Paper Issuance Matrix Audit#
- Benchmark 90-Day OIS Rates: USD SOFR = 4.550% (ACT/360); EUR ESTR = 2.650% (ACT/360); GBP SONIA = 4.700% (ACT/365F)
- Direct 90-Day USCP Dealer Quote (New York 144A / 4(a)(2)): 4.830% ACT/360 (= SOFR + 28.0 bps) -> Interest = $3,018,750
- Candidate 1 — Issue 90-Day EUR ECP @ 2.730% ACT/360 (ESTR + 8.0 bps) + EUR/USD FX Swap:
- Spot Ref S = 1.08500 (€230,414,747 issued); 90d EUR Repayment = €230,414,747 * (1 + 0.0273*90/360) = €231,987,327
- 90d EUR/USD FX Swap Ask Points (incl. -12.0bp basis + 0.20p spread) = +54.68 pips => F_swap = 1.090468!
- Contracted 90d USD Repayment = €231,987,327 * 1.090468 = $252,974,759!
- Exact All-In ACT/360 USD Rate = ($252,974,759 / $250,000,000 - 1) * (360 / 90) = 4.7596% (= SOFR + 20.96 bps!)
- NET SAVINGS VS DIRECT USCP = 28.00 - 20.96 = 7.04 bps ($44,000 saved on single 90-day $250M tranche!)
- Candidate 2 — Issue 90-Day AUD ECP @ 4.420% ACT/365F (AONIA + 12.0 bps) + POSITIVE +8.0bp AUD/USD Basis!
- Notice POSITIVE +8.0bp AUD basis SUBTRACTS 8.0 bps from synthetic USD funding cost!
- All-In Synthetic USD Spread = +12.0 bps (AUD CP spread) - (+8.0 bps basis) + 1.2 bps (swap ask) = SOFR + 5.2 bps!
Look at Candidate 2: when a currency exhibits a positive cross-currency basis (like AUD at +8 bps), swapping commercial paper or Kangaroo notes into USD subtracts the positive basis from the issuer's credit spread, achieving SOFR + 5.2 bps funding! Conversely, if December year-end approaches and the 3-month EUR/USD basis blows out from -12 bps to -42 bps, synthetic EUR-swapped USD jumps to SOFR + 51 bps—and the corporate treasurer immediately flips issuance 100% back to domestic New York USCP!
Operational Detail: Always Size the Far Swap Leg for Principal PLUS Foreign Interest!#
Look at Step 2 in our formula (€231,987,327 far leg vs €230,414,747 near leg): a zero-coupon discounted ECP note with €232.0M face value yields €230.4M cash proceeds on Day 0! You sell €230.41M on the Near Spot Leg to raise exact $250.00M today, and buy €231.99M on the Far 90-Day Leg so 100% of both foreign principal AND foreign CP interest is locked into USD with zero unhedged FX residual! Test daily SOFR compounding benchmarks in our SOFR overnight compounding & carry calculator.
Live Treasury Funding Matrix: 90-Day Synthetic USD Spreads Over SOFR#
| Issuance Currency & Market | Local Credit Spread (vs RFR) | 90-Day XCCY Basis ($x_{ccy}$) | FX Swap Ask Cost | All-In Synthetic USD Cost | Verdict vs USCP (+28bp) |
|---|---|---|---|---|---|
Domestic USD (USCP 4(a)(2)) | +28.0 bps (vs SOFR) | 0.0 bps | 0.0 bps | SOFR + 28.0 bps | Baseline Domestic Hurdle |
Euro EUR (STEP ECP) | +8.0 bps (vs €STR) | -12.0 bps (Cost +12bp) | +1.0 bps | SOFR + 21.0 bps | ISSUE EUR (-7.0 bps Save!) |
Sterling GBP (London ECP) | +14.0 bps (vs SONIA) | -11.0 bps (Cost +11bp) | +1.2 bps | SOFR + 26.2 bps | Marginal (-1.8 bps Save) |
Aussie AUD (ECP / ECD) | +12.0 bps (vs AONIA) | +8.0 bps (Gain -8bp!) | +1.2 bps | SOFR + 5.2 bps | BEST (-22.8 bps Save!) |
Yen JPY (Samurai CP, Dec Turn) | +4.0 bps (vs TONA) | -48.0 bps (YE Turn!) | +1.5 bps | SOFR + 53.5 bps | AVOID (+25.5 bps Loss!) |
Flipping the Trade: Asset-Side Sovereign Yield Pickup & Year-End Gating#
Notice the comment on that fourth KPI (Reverse arb: issue USD -> swap to JPY!): when USD/JPY basis hits -48 bps, USD issuers swap USD CP into ultra-cheap negative-rate Yen funding, while USD bond funds swap cash USD into FX-hedged Japanese T-Bills for SOFR + 48 bps—proven next in currency-hedged foreign sovereign bond yield pickup! Connect commercial paper issuance timing with quarter-end and year-end G-SIB FX swap turns and cross-currency basis CIP deviations on the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Who are the biggest real-world users of FX-swapped Euro Commercial Paper (ECP)?
European, Australian, Canadian, and Japanese commercial banks, supranational agencies (EIB, KfW, World Bank), and A1/P1 corporate treasuries dynamically toggle daily issuance between London STEP ECP and New York USCP based on real-time FX swap basis grids.
Why does a discounted zero-coupon ECP note require an slightly uneven FX swap?
If you issue €100,000,000 face value of 90-day zero-coupon ECP at 2.73%, investors wire you €99,322,126 on Day 0, and you repay €100,000,000 on Day 90. Your FX swap must sell €99.32M Spot and buy €100.00M Forward so zero EUR interest exposure remains!
How do US Money Market Fund (Rule 2a-7) reforms create arbitrage opportunities in FX swaps?
After SEC Rule 2a-7 institutional prime MMF reforms shrank unsecured bank USCP demand by over $800 billion, non-US banks faced wider USCP spreads in New York—making European ECP + FX swaps (or Federal Home Loan Bank / repo funding) critical arbitrage valves.
Does issuing foreign-currency ECP hedged with an FX swap create accounting income volatility under IFRS 9 / ASC 815?
Under IFRS 9 and US GAAP ASC 815 fair-value / cashflow hedge accounting, issuers separate the FX forward element and cross-currency "currency basis spread" into Other Comprehensive Income (Cost of Hedging Reserve), amortizing the synthetic interest cleanly!
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). Synthetic USD Commercial Paper Funding: FX Swap Implied SOFR Spread Math. QuantCalc Tools. https://quantcalctools.com/guides/synthetic-usd-commercial-paper-funding-fx-swap-implied-sofr-spreadRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
Currency-Hedged Foreign Sovereign Bond Yield Pickup: 3M Rolling FX Swap MathCovered Interest Parity Forwards
USD/CAD T+1 Spot Lag, Modified Following & End-of-Month FX Calendar MathCovered Interest Parity Forwards
FX Time-Option (Window) Forward Pricing: Worst-Case Swap Point Rule MathCovered Interest Parity Forwards
Mark-to-Market (MTM) Resetting Cross-Currency Basis Swap Notional MathCovered Interest Parity Forwards
Basel SA-CCR & ISDA SIMM v2.6 FX Forward Margin & Capital Drag MathCovered Interest Parity Forwards
Mark-to-Market (MTM) Valuation of Seasoned FX Forwards: Discounted PV MathCovered Interest Parity Forwards
ACT/360 vs ACT/365 FX Forward Day-Count Mismatch: GBP/USD & USD/CAD MathCagr Irr Drawdown Compounding
Expected Maximum Drawdown of Brownian Motion (Magdon-Ismail Drift Math)Cagr Irr Drawdown Compounding
Simple vs Modified Dietz Return Formula: Sub-Period Cashflow Weighting MathCagr Irr Drawdown Compounding
Hedge Fund 2-and-20 Fee Drag, High-Water Mark & Hurdle Net CAGR MathCagr Irr Drawdown Compounding
Treynor Ratio, Jensen’s Alpha & Modigliani M-Squared (M2) Leverage Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.