
Simple vs Modified Dietz Return Formula: Sub-Period Cashflow Weighting Math
When daily pre-flow portfolio valuations are unavailable on private credit or multi-custodian wealth accounts, Modified Dietz approximates True TWRR by day-weighting external cashflows.
How do institutional custodians, family offices, and pension consultants calculate Time-Weighted Rates of Return (TWRR) on accounts containing corporate bonds, private placements, or syndicated loans that are only priced at month-end while external client deposits and withdrawals arrive on Day 4, Day 11, and Day 26? Without intra-month portfolio valuations $V_k^{-}$ on the exact cashflow dates, exact geometric sub-period linking is impossible! Peter Dietz (1966) introduced the Simple Dietz midpoint approximation, which institutional custody systems refined into the Modified Dietz day-weighted return formula—historically embedded across CFA GIPS transition rules. Benchmark multi-year compounding in our CAGR Calculator and anchor in our CAGR, IRR & Drawdown Hub.
Exact Simple Dietz vs Modified Dietz Equations & Day-Weight Conventions#
Let $V0$ be beginning-of-month market value (including accrued income!), $V1$ be end-of-month market value across a $D$-day calendar month (e.g., $D = 30$ or $31$), and $CFk$ be external net cashflows arriving on day $dk \in [1, D]$. Notice the crucial difference between Simple Dietz (which blindly assumes every cashflow arrived at exact mid-month $wk = 0.50$) and Modified Dietz (which weights each cashflow by the exact fraction of the month $wk$ it sat invested in the portfolio):
- Net Investment Gain (Numerator for BOTH!) : Gain = V1 - V0 - Sum{k=1..M} CFk
- 1. Simple Dietz Return (Midpoint w = 0.5) : RSimple = Gain / [ V0 + 0.5 * Sum{k=1..M} CFk ]
- 2. Modified Dietz Return (Day-Weighted) : RMod = Gain / [ V0 + Sum{k=1..M} (wk * CF_k) ]
- End-of-Day Flow Convention : wk = (D - dk) / D
- Start-of-Day Flow Convention : wk = (D - dk + 1) / D (Must stay consistent across firm!)
- 3. Chain-Linked Annualized Modified Dietz : CAGRMod = [ Product{m=1..12} (1 + R_Mod,m) ]^(1/T) - 1
- Worked Intra-Month Crash Distortion Audit (30-Day April, V_0 = $10,000,000):
- Market rallies +10.0% from Day 0 to Day 6 (VDay6pre = $11,000,000), client wires +$5,000,000 on Day 6 EOD
- ($16,000,000 invested), then market crashes -15.0% from Day 6 to Day 30 -> Ending V_1 = $13,600,000!
- True Exact Sub-Period TWRR = (1 + 0.10) * (1 - 0.15) - 1 = 1.10 * 0.85 - 1 = -6.50%!
- Net Dollar Gain Numerator = $13,600,000 - $10,000,000 - $5,000,000 = -$1,400,000
- 1. Simple Dietz (w = 0.50) : -$1,400,000 / ($10.0M + 0.5*$5.0M) = -$1.40M / $12.50M = -11.20%! (-470 bps error!)
- 2. Modified Dietz (d_k = 6, EOD w = (30-6)/30 = 0.80):
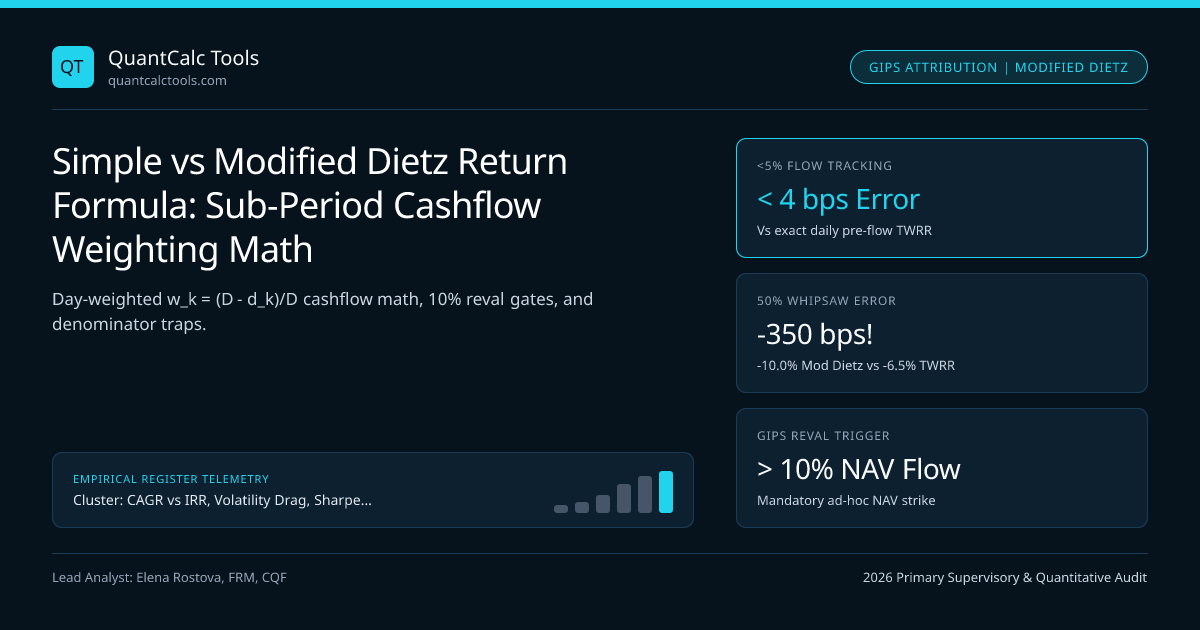
- R_Mod = -$1,400,000 / ($10.0M + 0.80*$5.0M) = -$1.40M / $14.00M = -10.00%! (-350 bps error vs True -6.50% TWRR!)
Pause and inspect why even Modified Dietz (-10.00%) missed True TWRR (-6.50%) by $-350\text{ bps}$ in that worked example! Modified Dietz is actually a first-order linear approximation to Money-Weighted IRR within that single month—implicitly assuming the portfolio returned a constant linear rate per day across all 30 days. When a large external cashflow ($+50\%$ of $V_0$) lands right at an intra-month market peak ($+10\%$ followed by $-15\%$), dollar-weighted intra-month loss leaks directly into Modified Dietz!
Exact Mathematical Error Bound of Modified Dietz: $\text{Error} \approx w(1-w)\,\frac{CF}{V0 + w\cdot CF}\,(R{\text{post}} - R_{\text{pre}})$#
Let $Ra$ be the pre-flow return on $[0, dk]$ and $Rb$ be the post-flow return on $[dk, D]$, with $c = CF / V_0$. Algebraic expansion proves that Modified Dietz equals Exact TWRR (Error = 0.00 bps) whenever ANY ONE of three conditions holds:
- External cashflow is zero ($c = 0$), OR cashflow occurs strictly at Day 0 ($w = 1$) or Day $D$ EOD ($w = 0$).
- Intra-month return rate was uniform (consistent with linear accrual, e.g., SOFR cash sweep).
- Both $|c|$ (
% cashflow size) and $|Rb - Ra|$ (intra-month volatility reversal) are small—because the approximation error is multiplicative inFlow Size x Intra-Month Return Reversal!
Modified Dietz vs True Daily TWRR Error Benchmarks by Cashflow Size#
Audit basis-point tracking gaps and redemption denominator hazards across escalating intra-month external cashflows:
| Cashflow Size ($CF / V_0$) | Intra-Month Regime ($R{\text{pre}}$ then $R{\text{post}}$) | True Exact TWRR | Modified Dietz ($d_k = 10/30$) | Simple Dietz ($w=0.5$) | Mod Dietz Error |
|---|---|---|---|---|---|
| $+2.0\%$ (Dividend / Fee) | $+2.0\%$ then $+1.0\%$ (Calm) | $+3.02\%$ | $+3.01\%$ | $+3.01\%$ | $-1\text{ bp}$ (Negligible) |
| $+8.0\%$ (Routine Inflow) | $+4.0\%$ then $-3.0\%$ (Mild) | $+0.88\%$ | $+0.69\%$ | $+0.73\%$ | $-19\text{ bps}$ |
| $+25.0\%$ (Large Allocation) | $+8.0\%$ then $-10.0\%$ (Whip) | $-2.80\%$ | $-4.44\%$ | $-4.71\%$ | $-164\text{ bps}$ (Breach!) |
| $+50.0\%$ (Major Mandate) | $+10.0\%$ then $-15.0\%$ (Crash) | $-6.50\%$ | $-10.00\%$ | $-11.20\%$ | $-350\text{ bps}$ (Severe!) |
| $-92.0\%$ (Near-Full Exit) | $-5.0\%$ then $+12.0\%$ (Snap) | $+6.40\%$ | Denominator Collapse! | Negative Denom! | Fails if $V_0 + w\cdot CF \le 0$! |
Look at Row 5 of the Table: The Catastrophic Denominator Trap on Large Redemptions!#
Suppose an account starts the month at $V0 = \$10.0\text{M}$, surges $+25\%$ to $\$12.5\text{M}$ on Day 3 (`wk = 0.90), and the client **withdraws $-\$11.5\text{M}$** (CF = -$11.5M), leaving $\$1.0\text{M}$ invested! Look at what happens to the Modified Dietz denominator: $$V_0 + w_k \cdot CF = \$10.0\text{M} + 0.90(-\$11.5\text{M}) = -\$0.35\text{M} < 0$$ Because the withdrawal exceeded $V_0 / w_k$ thanks to early intra-month profits, **the Modified Dietz denominator turns NEGATIVE**, printing an absurd **$-714\%$ return** on a month that made **$+25\%$**! Production portfolio engines MUST guard against V0 + Sum(wk * CFk) <= 0.10 * V0` by falling back to exact pre-flow revaluation or log-space XIRR!
GIPS Compliance Best Practices & Cross-Checks#
Compare Modified Dietz sub-period linking directly against TWRR vs XIRR cashflow attribution, verify fee-deducted net series using hedge-fund 2-and-20 net CAGR math, and check institutional verification protocols in verify and UK FCA guidance.
Frequently asked questions
Should Modified Dietz use start-of-day (D - d_k + 1)/D or end-of-day (D - d_k)/D cashflow weights?
Under GIPS, either convention (or exact timestamped intraday hour fraction) is valid PROVIDED it matches when capital actually enters market risk: subscription wires invested at the 4:00 PM market close earn zero return on day d_k (use (D - d_k)/D), whereas morning futures margin transfers trade all day d_k (use (D - d_k + 1)/D). Never mix conventions to cherry-pick returns!
Is Modified Dietz a Time-Weighted Return or a Money-Weighted Return?
Strictly speaking, WITHIN a single month, Modified Dietz is a linear approximation to Money-Weighted IRR! It becomes an approximation to Time-Weighted Return ONLY when you chain-link monthly (or weekly) Modified Dietz sub-periods geometrically: (1 + R_Jan)*(1 + R_Feb)*... - 1.
How must bond accrued interest and equity ex-dividends be treated in V_0 and V_1?
GIPS mandates trade-date accounting with full "dirty" market values (clean price PLUS accrued bond interest and declared ex-date dividends receivable) in BOTH V_0 and V_1! Omitting accrued interest causes artificial return spikes on coupon payment dates.
How does Modified Dietz support multi-currency Brinson attribution (Campisi / Ankrim-Hensel)?
Asset-segment Modified Dietz applies the exact same w_k denominator formula to each equity sector or bond bucket (treating internal buys/sells between sectors as segment cashflows!), guaranteeing that weighted sector Modified Dietz returns sum additively to exact total portfolio Modified Dietz return!
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). Simple vs Modified Dietz Return Formula: Sub-Period Cashflow Weighting Math. QuantCalc Tools. https://quantcalctools.com/guides/simple-vs-modified-dietz-sub-period-cashflow-weighting-accuracyRelated Cagr Irr Drawdown Compounding & Institutional Briefings
Explore Cagr Irr Drawdown Compounding Hub (20) →Cagr Irr Drawdown Compounding
CAGR vs IRR, Volatility Drag, Sharpe/Sortino & Drawdown Recovery: 2026 GuideCagr Irr Drawdown Compounding
Hedge Fund 2-and-20 Fee Drag, High-Water Mark & Hurdle Net CAGR MathCagr Irr Drawdown Compounding
Treynor Ratio, Jensen’s Alpha & Modigliani M-Squared (M2) Leverage MathCagr Irr Drawdown Compounding
Continuous Log Returns vs Simple Returns: Time Additivity vs Asset WeightsCagr Irr Drawdown Compounding
Fisher Exact Real CAGR, Inflation & Annual Tax Drag Compounding MathCagr Irr Drawdown Compounding
Arithmetic vs Geometric Mean Return: 0.5*Sigma^2 Variance Drain DerivationCagr Irr Drawdown Compounding
TWRR (CAGR) vs MWRR (XIRR): Irregular Cashflow Timing Divergence MathCagr Irr Drawdown Compounding
XIRR Newton-Raphson Convergence, Descartes Multiple Roots & MIRR MathKelly Margin Leverage Sizing
Short Naked Option Margin Math: Reg T 20%/10% Rule & Gamma Crash ExpansionKelly Margin Leverage Sizing
Repo Haircut, Rehypothecation Multiplier & Leveraged Bond Carry MathKelly Margin Leverage Sizing
Black-Litterman Posterior Expected Return & Bayesian Kelly Sizing MathKelly Margin Leverage Sizing
Guaranteed Stop-Loss Order (GSLO) Premium vs Gap Slippage & Option Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.