
DV01 & PVBP Formula: Why Dirty Invoice Price Scales Dollar Duration
Multiplying Modified Duration by quoted clean price instead of full dirty invoice price understates DV01 by up to 2.5% on high-coupon bonds just before coupon payment dates.
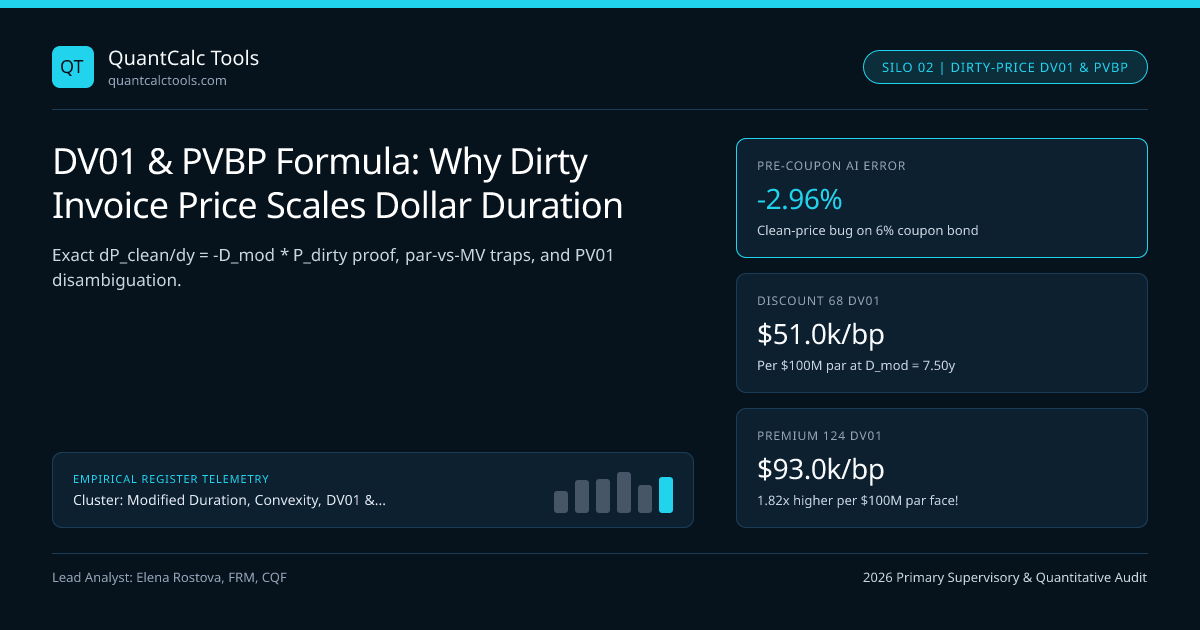
Ask ten junior fixed-income analysts to calculate the Dollar Value of a Basis Point (DV01) on $$100,000,000$ par face of a $6.00\%$ coupon bond trading at a clean price of $98.50$ five days before its semiannual coupon payment ($AI = 2.918$), and seven will multiply $D{mod} \times \$98,500,000 \times 0.0001$—leaving $$2,918,000$ of dirty invoice market value completely unhedged ($-2.96\%$ DV01 error)! Understanding why accrued interest cancels in $\Delta P$ yet must scale $D{mod}$ is mandatory for institutional swap and futures hedging under Key Rate Duration (KRD) & Partial DV01 Yield Curve Bucketing. Model funding cashflows in our SOFR overnight compounding & carry calculator and anchor this rule in our Modified Duration, Convexity & DV01 master guide.
Exact Calculus Proof: Why $\partial P{clean}/\partial y = -D{mod} \cdot P_{dirty}$#
Write the settlement cash invoice equation $P{dirty}(y) = P{clean}(y) + AI$, where accrued interest $AI = \frac{C}{k} \cdot \frac{\text{Days Accrued}}{\text{Days in Period}}$ depends strictly on the calendar settlement date and is mathematically constant ($\partial AI / \partial y = 0$) with respect to instantaneous yield shifts! Differentiating both sides with respect to yield $y$: $$\frac{\partial P{clean}}{\partial y} = \frac{\partial P{dirty}}{\partial y} - \underbrace{\frac{\partial AI}{\partial y}}{0} = -D{mod} \cdot P{dirty}$$ Notice the asymmetry! Because institutional risk engines define Macaulay Duration, Modified Duration & Second-Order Convexity as percentage sensitivity of total discounted cashflows ($D{mod} = -\frac{1}{P{dirty}}\frac{\partial P{dirty}}{\partial y}$), recovering dollar price change $\Delta P{clean} = \Delta P{dirty}$ for a $1\text{ bp} = 0.0001$ yield move requires multiplying back by $P{dirty}$, never $P{clean}$!
Worked Pre-Coupon Clean vs Dirty DV01 Hedge Slippage Audit ($100M Gilt)#
- Settlement: 5 Days Before Semiannual Coupon Payment (178 / 183 ACT/ACT ICMA Days Accrued)
- Clean Quoted Price (P_clean) = 98.5000 ($98,500,000 Clean Principal)
- Accrued Interest (AI) = 3.0000 * (178 / 183) = 2.918033 ($2,918,033 Accrued Cash!)
- Dirty Invoice Price (P_dirty)= 98.5000 + 2.918033 = 101.418033 ($101,418,033 Total Present Value)
- Modified Duration (D_mod) = 7.4200 years, Annualized Convexity (C) = 68.20
- 1) WRONG Clean-Price DV01 Formula (Common Spreadsheet Bug):
- DV01_wrong = $98,500,000 * 7.4200 * 0.0001 = $73,087.00 per bp
- 2) EXACT Tangent Dirty-Price DV01 Formula:
- DV01_tangent = $101,418,033 * 7.4200 * 0.0001 = $75,252.18 per bp (+2.962% larger!)
- 3) Discrete PVBP (Exact Price Value of a Basis Point for +1 bp Yield Increase):
- Delta_P(+1bp) = -$101,418,033 * [ -7.4200(0.0001) + 0.568.20*(0.0001)^2 ]
- = $75,252.18 - $34.58 (1bp convexity micro-term) = $75,217.60
- Symmetric Central-Difference DV01 = 0.5 * [ P(y - 0.5bp) - P(y + 0.5bp) ] = $75,252.18!
- 4) Unhedged PnL Slippage Across a +50 bps Central Bank Shock (Using Clean Bug):
- Unhedged DV01 Gap = $75,252.18 - $73,087.00 = $2,165.18 / bp => -$108,259 surprise loss!
Look at Step 4: on a routine $$100\text{M}$ high-coupon bond ticket settled near coupon date, scaling by clean price leaves $$2,165/\text{bp}$ unhedged—generating a $-$108,259$ P&L attribution break on a $50\text{ bps}$ rate move! Moreover, on the ex-dividend / coupon payment morning when $AI$ drops from $3.00$ to $0.00$ and $P{dirty}$ falls by $$3,000,000$, dirty-price DV01 exhibits a real physical step-change as the near-term $t \approx 0$ coupon leaves the bond (while $D{mod}$ jumps upward because a $t=0$ zero-duration cashflow dropped out, keeping $D{mod} \cdot P{dirty}$ nearly continuous!).
Terminology Disambiguation: DV01 vs PV01 vs PVBP vs BPV#
Trading desks across New York, London, and Frankfurt use four overlapping acronyms that cause costly API integration bugs unless strictly standardized:
Cross-Desk Comparison Matrix: DV01, PVBP, Swap PV01, and Signed BPV#
| Desk Metric Acronym | Exact Institutional Convention | Quotation Base Unit | Sign Convention | Primary Instrument Market |
|---|---|---|---|---|
| DV01 (Dollar Value of 01) | $-\frac{\partial P_{dirty}}{\partial y} \times 10^{-4}$ (Symmetric tangent) | Dollars per $$100$ par (or full ticket) | Positive for long bond | US Treasuries, Corporates, MBS |
| PVBP (Price Value of a Basis Point) | $P{dirty}(y) - P{dirty}(y + 1\text{ bp})$ (or $\pm 0.5\text{ bp}$) | Cents per $$100$ par face | Positive magnitude | Bloomberg YAS cash bond screen |
| PV01 (Present Value of 01) | Present value of a $1\text{ bp}$ ($0.01\%$) annuity stream | Dollars per $$100\text{M}$ swap notional | Positive annuity factor | Interest-rate swaps & CDS risky PV01 |
| BPV (Basis Point Value) | Signed PnL impact of a $+1\text{ bp}$ rate rise | Account currency ($/EUR/GBP) | Negative for long bond! | European risk & ISDA SIMM |
Pay special attention to PV01 on an Interest Rate Swap versus DV01 on a Discount/Premium Cash Bond: for a par swap, Swap DV01 closely matches the annuity PV01 of a $1\text{ bp}$ coupon stream; for an off-market deep-discount cash bond trading at $P{dirty} = 68.00$ per $100$ par, $$100\text{M}$ par face represents only $$68\text{M}$ of market value! Sizing a hedge from `$100M * Dmod instead of $68M * D_mod` over-hedges the discount bond by $+47.1\%$!
Sizing Exact DV01-Neutral Swap and Futures Hedges#
Once dirty-price dollar $DV01{bond}$ is computed on actual ticket notional, the DV01-neutral hedge units $H^*$ against an instrument quoting $DV01{hedge}$ per contract or per $$1\text{M}$ notional is $H^* = -\frac{DV01{bond}}{DV01{hedge}} \cdot \beta{yield}$, where $\beta{yield}$ adjusts for yield-beta spread volatility (e.g., $\beta \approx 0.94$ between 10Y Treasury yields and 10Y SOFR OIS swap rates!). Pair this calculation with par swap DV01 vs zero-rate PV01 Jacobian math and ACT/ACT ICMA vs 30/360 accrued-interest conventions, and explore the Modified Duration & Key-Rate Hedging Topic Hub.
Frequently asked questions
Why does dirty price scale DV01 even though bond trades are quoted in clean price?
Clean price equals Dirty Present Value minus Accrued Interest. When market yields jump +1 bp instantaneously on a fixed settlement date, Accrued Interest does not change by a single cent, so 100% of the dirty present-value change (-D_mod * P_dirty * 1bp) flows into clean price!
What happens to Modified Duration and DV01 on a coupon payment date?
The moment a coupon pays out, Dirty Price drops by the coupon cashflow while Modified Duration jumps upward (because a zero-duration t=0 cashflow just exited the weighted average). Those two opposing jumps nearly cancel in the product D_mod * P_dirty, keeping dollar DV01 smooth.
What is the difference between Swap PV01 (Annuity) and Swap DV01?
Annuity PV01 equals the discounted sum of day-count fractions across fixed-leg payment dates (value of 1 bp of fixed coupon). On a newly struck par OIS swap, Swap DV01 equals Annuity PV01 exactly; on a seasoned off-market swap, discounting the non-zero fixed-vs-float NPV adds a tiny tail adjustment.
Why should Treasury-to-SOFR swap hedges include a yield-beta multiplier?
A DV01-neutral 1:1 hedge assumes 10Y SOFR swap rates and 10Y Treasury yields move identically bp-for-bp. Empirically, swap spreads widen or tighten during flight-to-quality moves, so multiplying by regression beta (~0.92 to 1.05) minimizes realized variance.
Publication record
- Published
- 14 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). DV01 & PVBP Formula: Why Dirty Invoice Price Scales Dollar Duration. QuantCalc Tools. https://quantcalctools.com/guides/dollar-duration-dv01-pvbp-clean-vs-dirty-bond-price-scalingRelated Bond Duration Convexity Math & Institutional Briefings
Explore Bond Duration Convexity Math Hub (20) →Bond Duration Convexity Math
Modified Duration, Convexity, DV01 & Key-Rate Hedging: 2026 Quantitative GuideBond Duration Convexity Math
Second-Order Bond Convexity Formula: Taylor Error Under Large Yield ShocksBond Duration Convexity Math
Negative Convexity in Callable Bonds & Agency MBS: OAS Finite-Difference MathBond Duration Convexity Math
DV01-Neutral Barbell vs Bullet Portfolio: Convexity Pickup vs Yield MathBond Duration Convexity Math
Key-Rate Duration (KRD) Tent Functions: Partial DV01 Curve Bucketing MathBond Duration Convexity Math
50/50 vs Regression-Weighted 2s5s10s Butterfly Curve Trades: DV01 MathBond Duration Convexity Math
Cheapest-to-Deliver (CTD) Treasury Futures Conversion Factor & DV01 MathBond Duration Convexity Math
Leveraged Treasury Repo Carry, Curve Rolldown & Breakeven Yield Spike MathCovered Interest Parity Forwards
Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge MathCovered Interest Parity Forwards
Overnight (O/N), Tom-Next (T/N) & Spot-Next (S/N) T+2 FX Roll MathCovered Interest Parity Forwards
Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink MathCovered Interest Parity Forwards
Quarter-End & Year-End G-SIB Window-Dressing FX Swap Turn Premium Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.