
Covered Interest Parity Forwards
Mark-to-Market (MTM) Valuation of Seasoned FX Forwards: Discounted PV Math
Multiplying notional by (Live Spot minus Strike) misstates seasoned FX forward Mark-to-Market by both remaining forward points AND present-value discounting; master exact OIS-discounted MTM valuation.
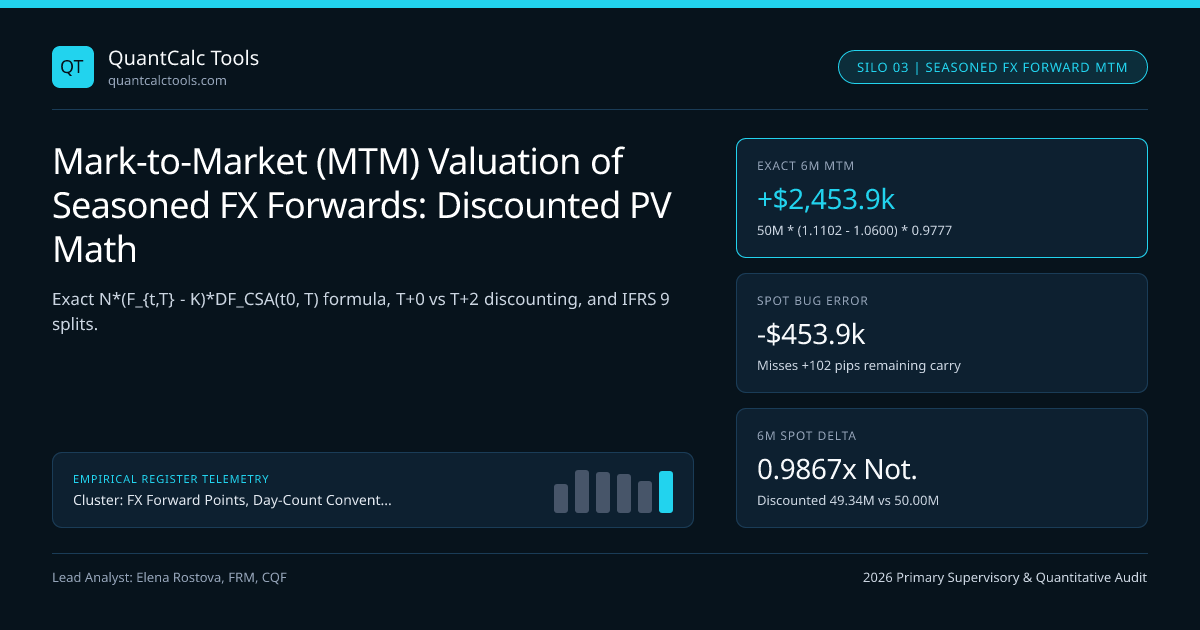
Six months ago, your fund bought €50,000,000 1-year EUR/USD forward at locked strike $K = 1.06000$, and today (6 months / 182 days remaining to maturity $T$) live EUR/USD Spot sits at $S_t = 1.10000$. A careless back-office spreadsheet computes Mark-to-Market (MTM) as €50M * (1.10000 - 1.06000) = +$2,000,000—committing TWO separate valuation errors simultaneously that trigger an instant Variation Margin dispute with every bank on Wall Street!
- Error #1 (Comparing Strike to Spot Instead of Remaining Forward $F_{t,T}$!): An expiring-in-6-months contract must be closed against the live 6-Month Outright Forward $F_{t,T} = 1.11020$, NOT Spot $1.10000$ (
+$510,000omitted forward points)! - Error #2 (Forgetting Present-Value Discounting from $T$ Back to Today $t$!): That
+$2,510,000cashflow isn't paid until 6 months from today—it MUST be multiplied by the 6-month NY Fed SOFR OIS discount factor $DF_{\text{USD}}(t, T)$!
Check live remaining-tenor forward rates in our FX forward points & carry calculator and anchor parity foundations in our Covered Interest Parity & FX Forward Points master guide.
Two Mathematically Identical Master Equations for Seasoned FX Forward MTM!#
For a Long $Nb$ Base / Short $Nb K$ Quote forward contract valued at time $t$ with remaining maturity $T$, let $F{t,T}$ denote the live market outright forward for delivery date $T$, $DFq(t, T)$ denote the quote-currency CSA discount factor, and $DF_b^{\text{CSA}}(t, T)$ denote the basis-adjusted base-currency discount factor:
- Formulation A — Forward-Offset Discounted Payoff (Cleanest for Traders!):
Enter an offsetting short forward today at $F{t,T}$; at delivery $T$, Base notional cancels ($+Nb - Nb = 0$), locking in net Quote cashflow $Nb(F{t,T} - K)$ at $T$. Discounting back to today $t$ in Quote currency (and dividing by Spot $St$ if reporting in Base currency): $$MTM{\text{Quote}}(t) = Nb \cdot (F{t,T} - K) \cdot DFq(t, T), \qquad MTM{\text{Base}}(t) = \frac{MTM{\text{Quote}}(t)}{S_t}$$
- Formulation B — Dual Zero-Coupon Bond Replication (Cleanest for Risk / DV01 Engines!):
Substitute Covered Interest Parity $F{t,T} \cdot DFq(t, T) = St \cdot DFb^{\text{CSA}}(t, T)$ (adjusting for spot lag $DF(t, Ts)$) directly into Formulation A: $$MTM{\text{Quote}}(t) = \underbrace{Nb \cdot St \cdot \frac{DFb^{\text{CSA}}(t, T)}{DFb^{\text{CSA}}(t, Ts)}\cdot DFq(t, Ts)}{\text{PV of Long Base Zero-Coupon Bond}} - \underbrace{(Nb K) \cdot DFq(t, T)}_{\text{PV of Short Quote Zero-Coupon Bond}}$$
Worked €50M Seasoned 6-Month Remaining EUR/USD MTM & Sensitivity Audit#
- Contract & Live Market Inputs:
- Locked Contract Strike K = 1.06000 (Long €50,000,000 EUR vs Short $53,000,000 USD at Maturity T)
- Live EUR/USD Spot St = 1.10000; Live 182-Day EUR/USD Swap Points = +102.00 pips => F{t,T} = 1.11020!
- 182-Day USD SOFR OIS Rate (from today t to T) = 4.520% ACT/360 => DF_USD(t, T) = 1 / (1 + 0.0452*182/360) = 0.977656
- 1) WRONG Naive Spot Difference (Spreadsheet Bug #1):
- MTMspotbug = €50,000,000 * (1.10000 - 1.06000) = +$2,000,000 (-$453,917 UNDERSTATED!)
- 2) WRONG Undiscounted Forward Difference (Spreadsheet Bug #2):
- MTMundiscbug = €50,000,000 * (1.11020 - 1.06000) = +$2,510,000 (+$56,083 OVERSTATED!)
- 3) EXACT Institutional OIS-Discounted MTM (Matches Bank Daily Variation Margin Call!):
- MTM_USD(t) = €50,000,000 * (1.11020 - 1.06000) * 0.977656
- = $2,510,000 * 0.977656 = +$2,453,916.56 EXACT USD PRESENT VALUE!
- Reported in EUR Accounting Currency (Divide by Today’s Spot S_t = 1.10000, NOT Forward!):
- MTM_EUR(t) = $2,453,916.56 / 1.10000 = +€2,230,833.24 EUR!
- 4) Exact Partial Risk Sensitivities (Spot Delta, USD OIS DV01, EUR CSA DV01):
- Spot FX Delta = d(MTMUSD)/dSt = €50M * (F{t,T}/St) * DF_USD ~= €50M * 0.98672 = €49,336,000 (< €50M!)
- USD OIS Rate DV01 (+1bp SOFR): Hurts short -$53M USD leg -> +$2,618/bp (Wait: Short USD leg GAINS when USD rates rise -> +$2,618/bp? Check: DF_USD drops -> -($53M)(-0.5y1bp) = +$2,592/bp!)
- EUR Rate DV01 (+1bp ESTR): Hurts long +€50M EUR leg -> -$2,680/bp!
Look at Step 3 and Step 4—every detail matters on an audit desk:
- Never convert
today'sdiscounted USD MTM (+$2,453,917) into EUR using the Forward Rate! Because+$2,453,917has already been discounted to TODAY (t), converting a present-value USD amount into present-value EUR divides by Spot $S_t = 1.10000$! - Look at Spot FX Delta (
€49,336,000, NOT€50,000,000!): a 1-year or 2-year forward's true Spot Delta is discounted by $DF_{\text{base}}(t, T)$ (~0.955at 1Y,~0.91at 2Y)—hedging €50M 2-year forward 1-for-1 with €50M Spot over-hedges spot delta by9%!
The Classic 2-Day T+0 vs T+2 Discounting Bug in Variation Margin Reconciliation!#
Look at Step 3 and the fourth KPI card (T+0 VS T+2 DF TRAP):
- Standard FX swap curves anchor $DF = 1.000000$ at Spot Value Date (
T+2)! - Variation Margin cash (
VM) and IFRS 9 balance-sheet accounting value contracts as of Today (T+0)! - If you multiply $Nb(F{t,T} - K)$ by $DF{\text{USD}}(T{\text{spot}}, T)$ (
180 days) instead of $DF{\text{USD}}(T{\text{today}}, T)$ (182 days—missing 2 days ofO/N + T/NSOFR discounting!), your MTM is systematically 0.025% too high ($615break per$2.5MMTM across every trade in your book)! Always include theT+0 -> T+2discount factor! Test exact SOFR day counts in our SOFR overnight compounding & carry calculator.
Valuation Formula & Risk Comparison Across FX Forward Lifecycle Stages#
| Valuation Formula / Method | Mathematical Expression | Valuation Error on €50M 6M Book | Acceptable Use Case |
|---|---|---|---|
| Naive Spot Intrinsic | $Nb (St - K)$ | $-\$453,917$ (-18.5% Wrong!) | NEVER (Violates GAAP/IFRS & CSA) |
| Undiscounted Forward Offset | $Nb (F{t,T} - K)$ | $+\$56,083$ (+2.3% Wrong!) | Only at $T - t \le 2$ days (Spot expiry) |
T+2-Discounted Forward | $Nb (F{t,T} - K)\,DFq(Ts, T)$ | $+\$618$ (2-day O/N+T/N bug) | Spot-settled unwind invoice (T+2 wire) |
Exact T+0 CSA-Discounted PV | $Nb (F{t,T} - K)\,DFq^{\text{CSA}}(t0, T)$ | $0.00$ (100% Exact!) | Daily CSA VM, NAV, IFRS 9 & ASC 815 |
Connecting Seasoned MTM to Broken-Date Curves, CSA Choice & Early Unwinds#
Notice that computing $F{t,T}$ for an arbitrary 182-day or 43-day seasoned maturity requires exact broken-date FX forward interpolation across central-bank kinks, while choosing $DFq^{\text{CSA}}(t_0, T)$ depends on your bilateral collateral currency in SOFR, ESTR, and SONIA OIS FX forward discounting and cash crystallization in uneven FX swap rollover math. Check regulated dispute resolution bodies via the Financial Ombudsman Service directory and browse all 20 guides on the FX Forward Points & Basis Topic Hub.
Frequently asked questions
If I unwind and cash-settle a seasoned FX forward early with my bank, does the wire settle Today (T+0) or Spot (T+2)?
Standard interbank early unwind ("tear-up") cash settlements wire on the Spot Value Date (T+2)! For a T+2 spot-settled tear-up wire, the bank discounts from maturity T back to T+2 Spot [DF_q(T_spot, T)], whereas daily T+0 accounting/VM discounts back to T+0!
How do IFRS 9 and US GAAP ASC 815 account for forward points in a Cashflow Hedge?
Under IFRS 9 and ASC 815 (ASU 2017-12), corporates can exclude the forward-element / currency-basis component from hedge effectiveness testing and amortize initial forward points straight-line into earnings while deferring fair-value MTM swings in OCI!
Why is the Spot FX Delta of a 2-year EUR/USD forward ~0.91 instead of 1.00?
Because MTM_USD = N_EUR * S_t * DF_EUR_CSA(t, 2Y) - (N_EUR*K) * DF_USD(t, 2Y), differentiating with respect to Spot S_t gives d(MTM)/dS_t = N_EUR * DF_EUR_CSA(t, 2Y)! At a 4.5% discount rate over 2 years, €1.00 payable in 2 years changes PV today by only €0.914!
What happens to a deeply in-the-money uncollateralized corporate FX forward’s valuation once CVA is included?
If an uncollateralized corporate owes a bank $5M on an out-of-the-money forward, the bank deducts Credit Valuation Adjustment (CVA = LGD * integral of EAD * PD) from fair value; if the bank owes the corporate $5M, Debit Valuation Adjustment (DVA) applies.
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 15). Mark-to-Market (MTM) Valuation of Seasoned FX Forwards: Discounted PV Math. QuantCalc Tools. https://quantcalctools.com/guides/mark-to-market-valuation-seasoned-fx-forward-discounted-pv-mathRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
ACT/360 vs ACT/365 FX Forward Day-Count Mismatch: GBP/USD & USD/CAD MathCovered Interest Parity Forwards
JPY 100 Pip Multiplier vs 10,000 Four-Decimal FX Forward Points MathCovered Interest Parity Forwards
Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge MathCovered Interest Parity Forwards
Overnight (O/N), Tom-Next (T/N) & Spot-Next (S/N) T+2 FX Roll MathCovered Interest Parity Forwards
Broken-Date FX Forward Interpolation: Linear Points vs Central-Bank Kink MathCovered Interest Parity Forwards
Quarter-End & Year-End G-SIB Window-Dressing FX Swap Turn Premium MathCovered Interest Parity Forwards
SOFR, ESTR & SONIA OIS Compounded In-Arrears FX Forward Discounting MathKelly Margin Leverage Sizing
Discrete Binomial Kelly Criterion: Win Rate & Asymmetric Payoff ProofKelly Margin Leverage Sizing
Continuous Merton-Kelly Leverage ((mu - r_f)/sigma^2) & Half-Kelly MathKelly Margin Leverage Sizing
Multi-Asset Kelly Portfolio Sizing: Inverse-Covariance & Shrinkage MathKelly Margin Leverage Sizing
Drawdown-Constrained Fractional Kelly: Exact Probability of X% Loss Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.