
Covered Interest Parity Forwards
USD/CAD T+1 Spot Lag, Modified Following & End-of-Month FX Calendar Math
Off-by-one calendar day bugs in FX forward engines misprice weekend and month-end swaps by 300%; master T+1 USD/CAD spot rules, split USD holiday exceptions, Modified Following, and End-of-Month rolls.
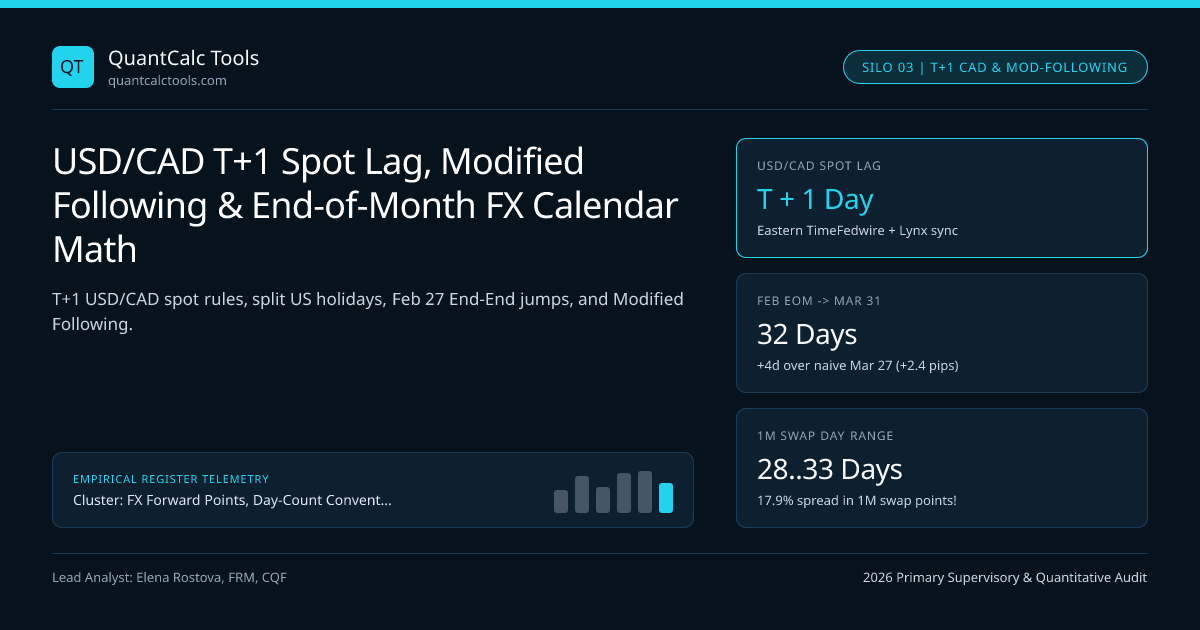
In institutional FX forward pricing, getting interest rates right to $0.1\text{ bps}$ is worthless if your Value Date Engine lands on the wrong calendar day—because landing on Friday May 29 instead of Monday June 1 changes elapsed accrual days $d$ from $28$ to $31$ days (+10.7% error on 1-month swap points!)! Four deterministic calendar algorithms defined in the ACI Model Code and EMTA/ISDA FX Definitions govern every spot and forward value date on earth: T+1 North American Spot Exceptions, Split USD Intermediate Holiday Rules, Modified Following (MF) Month-Boundary Clamps, and the End-of-Month (EOM / "End-End") Rule! Test exact day counts in our FX forward points & carry calculator and ground parity rules in our Covered Interest Parity & FX Forward Points master guide.
Exact 4-Step Algorithmic Specification of Institutional FX Value Dates#
Let $\mathcal{B}{A}$, $\mathcal{B}{B}$, and $\mathcal{B}_{\text{USD}}$ denote valid banking settlement days (excluding weekends and central-bank RTGS holidays: Fedwire for USD, TARGET2 for EUR, CHAPS for GBP, Lynx for CAD):
- Spot Lag (
T+1vsT+2):
T+1Pairs:USD/CAD,USD/TRY,USD/PHP,USD/RUBsettle Spot 1 joint business day after Trade Date (T+1in both currencies!).T+2Pairs (EUR/USD,GBP/USD,USD/JPY,EUR/GBP): Step forward 2 business days in non-USD currencies, AND verify the final Spot date is a validFedwireUSD day! (Crucial subtlety: forEUR/USD, ifT+1is a US-only holiday like Veterans Day or Columbus Day while FrankfurtTARGET2is open,T+1STILL COUNTS toward EUR's 2 days—so Monday trade settles WednesdayT+2! Only ifT+2itself is a US holiday does Spot roll to Thursday!)
- Forward Tenor Roll (
1M,3M,6M,1Y) from Spot Date $T_s$:
- Rule A — End-of-Month (
EOM/ End-End Rule): If Spot Date $T_s$ is the last valid joint business day of its calendar month (e.g., Friday Feb 27, 2026, since Feb 28 is Saturday!), then1M,2M,3Mforwards MUST land on the last valid joint business day of the target month (Mar 31, Apr 30, May 29—NOT Mar 27!)! - Rule B — Modified Following (
MF): When $Ts$ is not month-end, add $m$ months to $Ts$'s day-of-month; if that date is a weekend or holiday in either currency (or USD for crosses!), roll forward to the next joint business day UNLESS rolling forward crosses into the NEXT calendar month—in which case roll BACKWARD to the last joint business day of the target month!
Worked February Leap/Non-Leap EOM & Modified Following Edge-Case Audit#
- Edge Case 1 — The "End-End" February Trap (Trade Date: Wednesday, Feb 25, 2026):
- 1) EUR/USD (T+2): Spot Date T_s = Friday, Feb 27, 2026.
- Wait: Feb 2026 has 28 days, and Saturday Feb 28 is a weekend!
- Therefore Friday Feb 27 IS THE LAST BUSINESS DAY OF FEBRUARY -> Triggers EOM = TRUE!
- Naive "Same-Day +1 Month" Code: Picks Friday, March 27, 2026 -> d = 28 days (WRONG BY 4 DAYS!)
- Exact ACI End-End Rule: Picks Tuesday, MARCH 31, 2026 -> d = 32 days!
- At +0.60 pips/day on EUR/USD: 32d (+19.20p) vs 28d (+16.80p) = 2.40 PIPS ERROR ($24,000 per €100M)!
- 2) USD/CAD (T+1!) Executed on the EXACT SAME Wednesday, Feb 25, 2026:
- Spot Date T_s = Thursday, Feb 26, 2026! (Friday Feb 27 is still open -> EOM = FALSE!)
- > 1M USD/CAD Forward lands on Thursday, MARCH 26, 2026 (d = 28 days)!
- (Notice USD/CAD must wait until THURSDAY Feb 26 trade date for Spot to hit Feb 27 EOM!)
- Edge Case 2 — Modified Following Month-End Backward Clamp:
- Spot Date T_s = Thursday, April 30, 2026 (EOM = TRUE) -> 1M Target = May 31, 2026 (Sunday!).
- Following Rule would roll May 31 (Sun) -> Monday, JUNE 1, 2026 (Crosses into June — FORBIDDEN!).
- Modified Following Clamps BACKWARD -> Friday, MAY 29, 2026 (d = 29 days instead of 32 days)!
Read Edge Case 1 again—that single February 27 vs March 31 test separates Tier-1 bank libraries from broken GitHub scripts! Because February 28, 2026 falls on a Saturday, Friday February 27th IS Month-End, jumping 1M forward delivery all the way from March 27 to March 31 (+4 extra accrual days, +$24,000 per €100M)!

Subtle Exception #4: Weekly Tenors (1W, 2W, 3W) Use Pure Following (Never Modified Following)!#
Look at that fourth KPI card (WEEKLY TENORS = Exact Follow!):
- Monthly & Yearly Tenors (
1M..1Y) obey Modified Following + EOM. - Weekly Tenors (
1W = +7d,2W = +14d,3W = +21d) obey Pure Following (Followingwithout month-boundary clamping and without EOM): ifSpot + 7 dayslands on Sunday May 31, a1Wswap DOES roll forward across the month boundary to Monday June 1 (8 days, never Friday May 295 days)! Why? Because clamping a 7-day swap backward by 2 days into May 29 would chop a 1-week trade down to 5 days!
Global Spot Lag & Settlement Holiday Calendar Reference Matrix#
| Currency Pair | Spot Lag | Primary Holiday Calendars Checked | Intermediate T+1 USD Holiday Rule | EOM Rule Applies to 1M+? |
|---|---|---|---|---|
USD/CAD ("Funds") | T+1 | US Fedwire + Canada Lynx (Toronto) | No T+1 intermediate step (T+1 IS Spot!) | Yes (Spot on last bus. day) |
USD/TRY, USD/PHP | T+1 | US Fedwire + Istanbul / Manila | Direct T+1 joint business day | Yes |
EUR/USD | T+2 | Eurozone TARGET2 + US Fedwire | US T+1 holiday ignored if TARGET2 open! | Yes |
USD/JPY | T+2 | Japan BOJ-NET (Tokyo) + US Fedwire | US T+1 holiday ignored if Tokyo open! | Yes (Watch May Golden Week!) |
EUR/GBP (Cross) | T+2 | TARGET2 + UK CHAPS + US Fedwire! | CLS settles via USD/joint window (Fedwire checked!) | Yes |
Pairing Value-Date Calendars with ACT/365F CAD Day Counts & Pre-Spot Rolls#
Remember that USD/CAD combines T+1 Spot settlement (Thursday 3x weekend roll, proven in Overnight, Tom-Next, and Spot-Next roll math) with ACT/365F CAD vs ACT/360 USD day counts (proven in ACT/360 vs ACT/365 FX forward day-count mismatch)! Verify Canadian regulatory rules via the British Columbia Securities Commission, test overnight rates in our SOFR compounding & carry calculator, and browse the FX Forward Points & Basis Topic Hub.
Frequently asked questions
Why does USD/CAD settle on T+1 ("Funds") while EUR/USD and USD/JPY settle on T+2?
New York and Toronto share the exact same Eastern Time Zone (UTC-5) and tightly linked North American payment clearing (Fedwire and Payments Canada Lynx), allowing bilateral FX settlement within 24 hours without cross-continent time-zone cutoffs.
Why are US Fedwire holidays checked even when trading a non-USD cross like EUR/GBP?
Because the vast majority of institutional cross-currency trades hedge via two USD legs or settle through CLS Bank multilateral netting windows tied to North American hours, interbank convention avoids settling standard EUR/GBP spot or pillar dates on US Fedwire holidays.
What is a "Split Settlement" FX date when a currency holiday is declared unexpectedly?
If a country declares an emergency one-off holiday AFTER a forward contract was already struck, one currency leg delivers on the original date while the closed-country currency leg delivers on the next open business day—creating 1-day overnight credit/Herstatt exposure unless CLS-adjusted.
How does Japan’s Golden Week (May 3–6) affect USD/JPY Spot and 1-Week swap points?
A USD/JPY Spot trade executed just before Golden Week can take 6 to 7 calendar days simply to reach T+2 Spot! While Spot itself still carries zero swap points by definition, Tom-Next rolls across Golden Week accrue 5x to 6x normal overnight interest!
Publication record
- Published
- 13 November 2026
- Updated
- 15 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 15). USD/CAD T+1 Spot Lag, Modified Following & End-of-Month FX Calendar Math. QuantCalc Tools. https://quantcalctools.com/guides/usd-cad-t1-spot-lag-holiday-calendar-modified-following-fx-forwardsRelated Covered Interest Parity Forwards & Institutional Briefings
Explore Covered Interest Parity Forwards Hub (20) →Covered Interest Parity Forwards
Covered Interest Parity, FX Forward Points & Cross-Currency Basis: 2026 GuideCovered Interest Parity Forwards
FX Time-Option (Window) Forward Pricing: Worst-Case Swap Point Rule MathCovered Interest Parity Forwards
Mark-to-Market (MTM) Resetting Cross-Currency Basis Swap Notional MathCovered Interest Parity Forwards
Basel SA-CCR & ISDA SIMM v2.6 FX Forward Margin & Capital Drag MathCovered Interest Parity Forwards
Mark-to-Market (MTM) Valuation of Seasoned FX Forwards: Discounted PV MathCovered Interest Parity Forwards
ACT/360 vs ACT/365 FX Forward Day-Count Mismatch: GBP/USD & USD/CAD MathCovered Interest Parity Forwards
JPY 100 Pip Multiplier vs 10,000 Four-Decimal FX Forward Points MathCovered Interest Parity Forwards
Cross-Currency Basis Swap Deviation: Covered Interest Parity Wedge MathCagr Irr Drawdown Compounding
Hedge Fund 2-and-20 Fee Drag, High-Water Mark & Hurdle Net CAGR MathCagr Irr Drawdown Compounding
Treynor Ratio, Jensen’s Alpha & Modigliani M-Squared (M2) Leverage MathCagr Irr Drawdown Compounding
Continuous Log Returns vs Simple Returns: Time Additivity vs Asset WeightsCagr Irr Drawdown Compounding
Fisher Exact Real CAGR, Inflation & Annual Tax Drag Compounding Math
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.