
Repo Haircut, Rehypothecation Multiplier & Leveraged Bond Carry Math
A 2.0% Treasury repo haircut unlocks 50x theoretical balance-sheet leverage—until a haircut hike to 6.0% forces an instant two-thirds fire sale; master exact repo carry and haircut-run math.
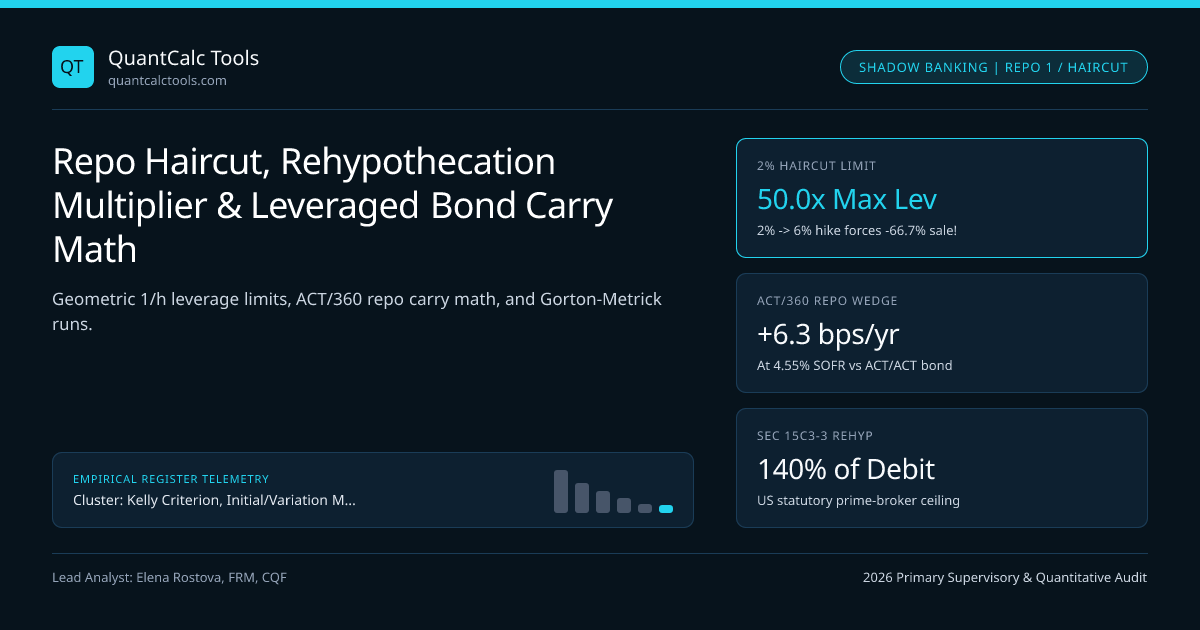
Fixed-income relative-value hedge funds (cash-futures Treasury basis trades, swap-spread arbitrage, and sovereign curve rolldown desks) routinely run 15x to 50x gross balance-sheet leverage financed in the $4+ trillion daily Repurchase Agreement (Repo) market. How does $1 of fund equity control $50 of US Treasury notes, how do ACT/360 repo financing rates interact with ACT/ACT bond yields, and why did Gary Gorton and Andrew Metrick (2012) identify Repo Haircut Increases as the core mathematical trigger of the 2008 shadow-banking run? Model repo financing spreads in our SOFR Compounding & Carry Calculator, inspect the Leveraged Treasury Repo Carry & Rolldown Engine, and consult our Kelly, Margin & Liquidation Hub.
Exact Geometric Series of Repo Leverage (1 / h), Leveraged ROE & Breakeven Yield Shock#
When a fund pledges $100 market value of securities with repo haircut $h \in (0, 1)$ (or lending value $1 - h$), the repo lender advances $(1 - h) * 100 in cash, requiring the fund to supply $h * 100 of its own equity per turnover round. Looping repo cash to purchase more bonds (1 + (1-h) + (1-h)^2 + ...) converges via an exact infinite geometric series to Maximum Balance-Sheet Leverage $L_{\max} = 1 / h$ (in practice executed in a single DVP Simultaneous Settlement ticket!):
- 1. Infinite Repo Pyramid / DVP Limit (Haircut h in (0, 1), Equity E_0):
- Max Bond Assets Bmax = E0 * [ 1 + (1 - h) + (1 - h)^2 + ... ] = E0 / h => Max Leverage Lmax = 1 / h !
- Repo Borrowed Cash = Bmax - E0 = E0 * [ (1 - h) / h ] = (L - 1) * E0
- 2. Exact Leveraged Bond Carry + Rolldown ROE (Accounting for ACT/360 Repo vs ACT/ACT Yield!):
- Effective Annualized Repo Cost : rrepo,eff = rrepo,quote * (365 / 360) [Simple daily roll: (1 + r*1/360)^365 - 1]
- Leveraged Net ROE : ROE(L) = ybondcarryroll + (L - 1) * ( ybondcarryroll - r_repo,eff )
- = rrepo,eff + L * ( ybondcarryroll - r_repo,eff )
- 3. Gorton-Metrick (2012) Haircut-Shock Forced De-Leveraging (Haircut jumps h0 -> h1 on Fixed Equity E_0!):
- ForcedAssetLiquidation% = 1 - (h0 / h1) => Dollar Fire Sale = E0 * (1/h0 - 1/h1)!
- Worked Treasury Relative-Value Repo Audit ($20M Fund Equity, h_0 = 2.0% Haircut, Operating at L = 25x => $500M Bonds):
- Bond Carry + Rolldown = 4.82% (ACT/ACT), General Collateral SOFR Repo = 4.55% (ACT/360 -> 4.613% eff, or 4.72% compounded!):
- Net Leveraged ROE = 4.72% + 25 * (4.82% - 4.72%) = 4.72% + 2.50% = +7.22% (Plus +12 bps futures basis convergence = +10.22%!)
- Crisis Haircut Shock (Dealer hikes haircut from h0 = 2.0% to h1 = 6.0% overnight, ZERO equity injection available):
- Max Supportable Assets shrinks from $20M / 0.02 ($1,000M cap; $500M actual) down to $20M / 0.06 = $333.3M!
- Forced Overnight Bond Fire Sale = $500.0M - $333.3M = $166.7M (-33.3% of book dumped at market WITHOUT any bond default!)
Gorton-Metrick Repo Haircut Runs & Forced Balance-Sheet Deleveraging#
Look at Equation 3 (Forced Sale = 1 - h_0 / h_1): if a structured-credit fund operates near max leverage at h_0 = 2% (50x) and dealers hike haircuts to h_1 = 10% (10x), the fund is mathematically forced to dump 80.0% (1 - 2/10) of its entire bond portfolio by tomorrow morning even if fundamental default probabilities barely moved! In 2007–2008, non-agency ABS repo haircuts jumped from 2% to 45%+, collapsing shadow-banking money creation overnight!
Don't Miss the ACT/360 Repo vs ACT/ACT Bond Yield Day-Count Trap!#
In tight 8–15 bps leveraged sovereign carry trades, forgetting that USD & EUR Repo rates accrue on ACT/360 while US Treasury & German Bund coupons accrue on ACT/ACT ICMA flips a seemingly profitable levered trade into a money loser! At a quoted 4.55% SOFR repo rate, over 365 calendar days you actually pay $4.55\% \times (365/360) =$ 4.613% simple (4.72% daily compounded)—erasing 6.3 to 17 bps of apparent positive carry before 25x leverage multiplies that error! (Same exact day-count physics as our ACT/360 vs ACT/365 FX forward guide!)
Institutional Repo Haircut Schedule & Maximum Leverage Ceilings (Tri-Party / Bilateral)#
Inspect typical institutional repo haircuts (h), theoretical 1/h balance-sheet limits, and prudent institutional operating leverage (<= 0.5x L_max):
| Collateral Security Class | Typical Calm Repo Haircut ($h_0$) | Crisis Stressed Haircut ($h_{\text{stress}}$) | Theoretical Max ($1/h_0$) | Prudent Fund Leverage | Rehypothecation Velocity ($v$) |
|---|---|---|---|---|---|
US Treasury Bills / Notes (< 10Y) | $0.5\%\text{--}2.0\%$ (0% FICC!) | $2.0\%\text{--}4.0\%$ | 50x – 200x | 15x – 35x (Basis pods) | High (2.2x – 3.0x Singh IMF) |
| 30-Year Sovereigns / TIPS / Gilts | $3.0\%\text{--}5.0\%$ | $7.0\%\text{--}12.0\%$ | 20x – 33x | 8x – 15x | Moderate-High |
Agency MBS (FNMA / GNMA) | $3.0\%\text{--}5.0\%$ | $8.0\%\text{--}15.0\%$ | 20x – 33x | 6x – 12x (mREITs) | Moderate |
| Investment-Grade Corporate Bonds | $6.0\%\text{--}10.0\%$ | $15.0\%\text{--}25.0\%$ | 10x – 16.7x | 4x – 7x | Low-Moderate |
| High-Yield Credit / Equities | $15.0\%\text{--}30.0\%$ | $40.0\%\text{--}100\%$ (No Roll!) | 3.3x – 6.7x | 1.5x – 3.0x | Capped (140% SEC 15c3-3) |
Look at Bar 1 Above: Why 25x Repo Leverage Can ONLY Exist Alongside a DV01 Hedge!#
On a 5-Year Treasury Note with Modified Duration = 4.40, 25x unhedged repo leverage multiplies portfolio duration to *`25 4.40 = 110.0 years**—meaning a routine **+9.1 bps morning CPI selloff wipes out 100% of fund equity**! Institutional pods run 25x repo **strictly against an offsetting DV01`-matched Short Treasury Future or Pay-Fixed OIS Swap**, turning directional duration risk into hedged basis convergence while pre-funding CCP Variation Margin cash buffers and CME SPAN 2 futures Initial Margin!
Frequently asked questions
What is the difference between General Collateral (GC) Repo and "Special" Repo?
General Collateral (GC) repo lends cash against any interchangeable basket of US Treasuries near NY Fed SOFR (~4.55%). When one specific Treasury CUSIP (often the on-the-run 10Y or Cheapest-to-Deliver futures bond) is heavily shorted and scarce, cash lenders accept 1.0% or even -3.0% interest ("trading special") just to borrow that specific bond!
What is "rehypothecation" and how does Manmohan Singh’s Collateral Velocity work?
When Hedge Fund A pledges $100M of Treasuries to Prime Broker X, and Prime Broker X re-pledges ("rehypothecates") those same Treasuries to Money Market Fund Y to borrow cash, the same $100M bond backs $200M+ of credit transactions (Collateral Velocity v ~= 2.0–3.0)—amplifying liquidity in booms and deleveraging when clients revoke rehypothecation rights!
How does the SEC’s US Treasury Central Clearing mandate change hedge fund basis-trade repo?
Historically, many bilateral dealer-to-hedge-fund Treasury repos traded at 0.0% haircut ("zero-haircut repo") outside central clearing. Mandatory FICC clearing requires standardized clearinghouse Initial Margin / haircuts across covered Treasury repos while expanding multilateral balance-sheet netting for dealers.
Why did Silicon Valley Bank (SVB) fail without repo haircut runs while LTCM and Bear Stearns failed via repo?
Bear Stearns and LTCM funded assets with short-term overnight repo—when repo lenders hiked haircuts or refused to roll overnight, cash vanished in 48 hours. SVB funded long-duration MBS with uninsured demand deposits that wired out in 24 hours after unhedged duration losses exceeded equity!
Publication record
- Published
- 13 November 2026
- Updated
- 14 November 2026
- Author
- Elena Rostova, FRM, CQF
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Elena Rostova, FRM, CQF. (2026, November 14). Repo Haircut, Rehypothecation Multiplier & Leveraged Bond Carry Math. QuantCalc Tools. https://quantcalctools.com/guides/repo-haircut-rehypothecation-multiplier-maximum-balance-leverageRelated Kelly Margin Leverage Sizing & Institutional Briefings
Explore Kelly Margin Leverage Sizing Hub (20) →Kelly Margin Leverage Sizing
Kelly Criterion, Initial/Variation Margin & Liquidation Math: 2026 GuideKelly Margin Leverage Sizing
Black-Litterman Posterior Expected Return & Bayesian Kelly Sizing MathKelly Margin Leverage Sizing
Guaranteed Stop-Loss Order (GSLO) Premium vs Gap Slippage & Option MathKelly Margin Leverage Sizing
Discrete Binomial Kelly Criterion: Win Rate & Asymmetric Payoff ProofKelly Margin Leverage Sizing
Continuous Merton-Kelly Leverage ((mu - r_f)/sigma^2) & Half-Kelly MathKelly Margin Leverage Sizing
Multi-Asset Kelly Portfolio Sizing: Inverse-Covariance & Shrinkage MathKelly Margin Leverage Sizing
Drawdown-Constrained Fractional Kelly: Exact Probability of X% Loss MathKelly Margin Leverage Sizing
UK FCA COBS 22.5 & ESMA Retail Leverage Caps & 50% Margin Close-Out MathIPO and Funding
Anthropic IPO Valuation Could Be Slashed in Half to $1T After AI Stock Rout: ReportIPO and Markets
Anthropic's $1.5 trillion IPO valuation in doubt after tech sell-off hammers the marketRegulatory Benchmarks
UK & Quantitative Margin-Regulated Execution 2026 Licensing Benchmark: 6D Prudential Scorecard Across 57 Audited EntitiesCompliance Forensics
How to Verify UK & Quantitative Margin-Regulated Execution Licences & Detect Clone Firms: 2026 Supervisory Lookup Playbook
QuantCalc Tools Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.